Loading...
HOME2023-01-22T13:43:33-07:00

“Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.

I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.

I still remember how it started for me. It started in June of 2008. After 11  years …..Click to continue

Mortgage Today (AM) - 10/01/26 {{catlist}}
October 1, 2026
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 10/01/2026** Bond markets are selling off without clear economic justification, with the 10-year Treasury at 5.303% after rising 56 basis points in September and MBS prices down roughly 0.25 points as investors grapple with technical and flow-driven selling rather than fundamental deterioration. UMBS coupons are mixed; the 6.5% coupon held at 100.66 with modest intraday gains, while lower coupons like 5.5% slipped to 95.22, reflecting the bear-steepening yield curve and duration-driven losses. GNMA prices track similarly with the 6.0% coupon at 98.26 and the 6.5% holding near par, though the broader market momentum favors waiting for a stronger technical rally before adjusting lock-float strategies. Economic data delivered conflicting signals that failed to arrest the selloff: jobless claims improved to 197,000, continuing claims at 1.701 million, core PCE undershot expectations at 3.0%, yet personal spending surged and Q2 GDP revised sharply higher to 2.2%, none of which shifted market direction meaningfully. The yield curve continued its bear-steepening trajectory with the 2s10s spread at roughly +40 basis points, a structural headwind for mortgage spreads as duration rather than credit risk drove the session. Hedge strategies focusing on options protection, such as CME Eris Options, are becoming increasingly critical as mortgage companies navigate basis risk between warehouse inventory and uncertain secondary market valuations. New York Life Investment Management is taking majority control of Invictus Capital Partners, the company behind Verus Mortgage Capital, signaling substantial institutional capital flowing into the non-Agency space despite rate volatility. Verus is on track for its biggest securitization year with approximately $8.9 billion across 14 deals in 2026, demonstrating resilient investor appetite for residential mortgage credit outside the Agency channel. This institutional consolidation mirrors broader market trends where lenders are shifting focus toward non-QM and DSCR lending as Agency margins compress and secondary market opportunities stabilize. Federal Housing Finance Agency Director Bill Pulte announced that Fannie Mae and Freddie Mac will consolidate to a single pricing grid incorporating VantageScore alongside FICO Classic scoring, effective immediately for new lenders applying to the program. The GSEs also granted a temporary exception to the November 2 Uniform Appraisal Dataset 3.6 deadline following MBA concerns about ecosystem readiness, pushing compliance pressures back for originators managing appraisal workflows. These policy shifts underscore ongoing modernization of GSE credit frameworks, which directly impacts origination economics and title and settlement operations nationwide. Mortgage technology companies are racing to address operational friction in non-Agency lending, with Friday Harbor launching AI-powered pre-underwriting for DSCR and investor loans, while Newfi partners with Addy AI to automate decision-making and streamline operations. LoanPASS AUS launched to provide deterministic, rules-based automated underwriting for loans outside traditional Agency platforms, targeting the complex documentation issues that derail files before formal underwriting reviews. These automation investments signal that lenders treating non-QM as a strategic channel—rather than a niche product—are gaining structural advantages in cost control and speed-to-close. Spec pay-ups continue deteriorating with no clear bottom, declining 0.50 to 0.70 in implied value since late August, forcing capital markets teams to recalibrate pricing strategies before losses materialize on profit-and-loss statements. Loan officers building relationships with investor borrowers and self-employed earners will command premium margins as institutional capital seeks seasoned operators with established portfolio flows and demonstrated servicing expertise. The convergence of technology automation and investor portfolio growth is reshaping origination fundamentals: those who build repeatable workflows today will own the non-Agency channel when rate normalization returns. **Locking vs Floating** Markets remain structurally challenged without clearer economic signals to justify a sustained rally. Maintain a neutral lock-float position until bond prices demonstrate an appetite to recover on their own merit rather than simply bouncing from oversold technicals. If weak economic data materializes alongside a bond recovery, expect meaningful mortgage rate compression, which justifies patience over aggressive rate locks. **Today's Events** Continued Claims (Sep/19): 1,701K vs 1,730K forecast, 1,719K previous Jobless Claims (Sep/26): 197K vs 200K forecast, 197K previous September S&P Global U.S. Manufacturing PMI August Construction Spending September ISM Manufacturing Index Fed Presidents speaking: Barkin, Collins, Schmid, Waller, Jefferson, Bowman, Williams, Cook, Logan Treasury bond buyback (up to $6 billion announced) **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | **UMBS 30-Year** | Coupon | Price | Intra-Day Change | |:---:|:---:|:---:| | 5.5 | 95.22 | -0.18 | | 6.0 | 98.04 | 0.02 | | 6.5 | 100.66 | 0.10 | **GNMA 30-Year** | Coupon | Price | Intra-Day Change | |:---:|:---:|:---:| | 5.5 | 95.52 | 0.02 | | 6.0 | 98.26 | -0.03 | | 6.5 | 100.40 | 0.08 | **U.S. Treasuries** | Term | Yield | Price | Intra-Day Yield Change | |:---:|:---:|:---:|:---:| | 2-Year | 4.869 | 99.775 | -0.03 | | 3-Year | 4.988 | 98.312 | -0.013 | | 5-Year | 5.091 | 99.604 | -0.002 | | 7-Year | 5.205 | 98.812 | 0.016 | | 10-Year | 5.315 | 94.703 | 0.028 | | 30-Year | 5.673 | 92.151 | 0.040 | Stay ahead of market shifts—subscribe free at WellThatMakesSense.com. Market Data
Mortgage Today (PM) - 09/30/26 {{catlist}}
September 30, 2026
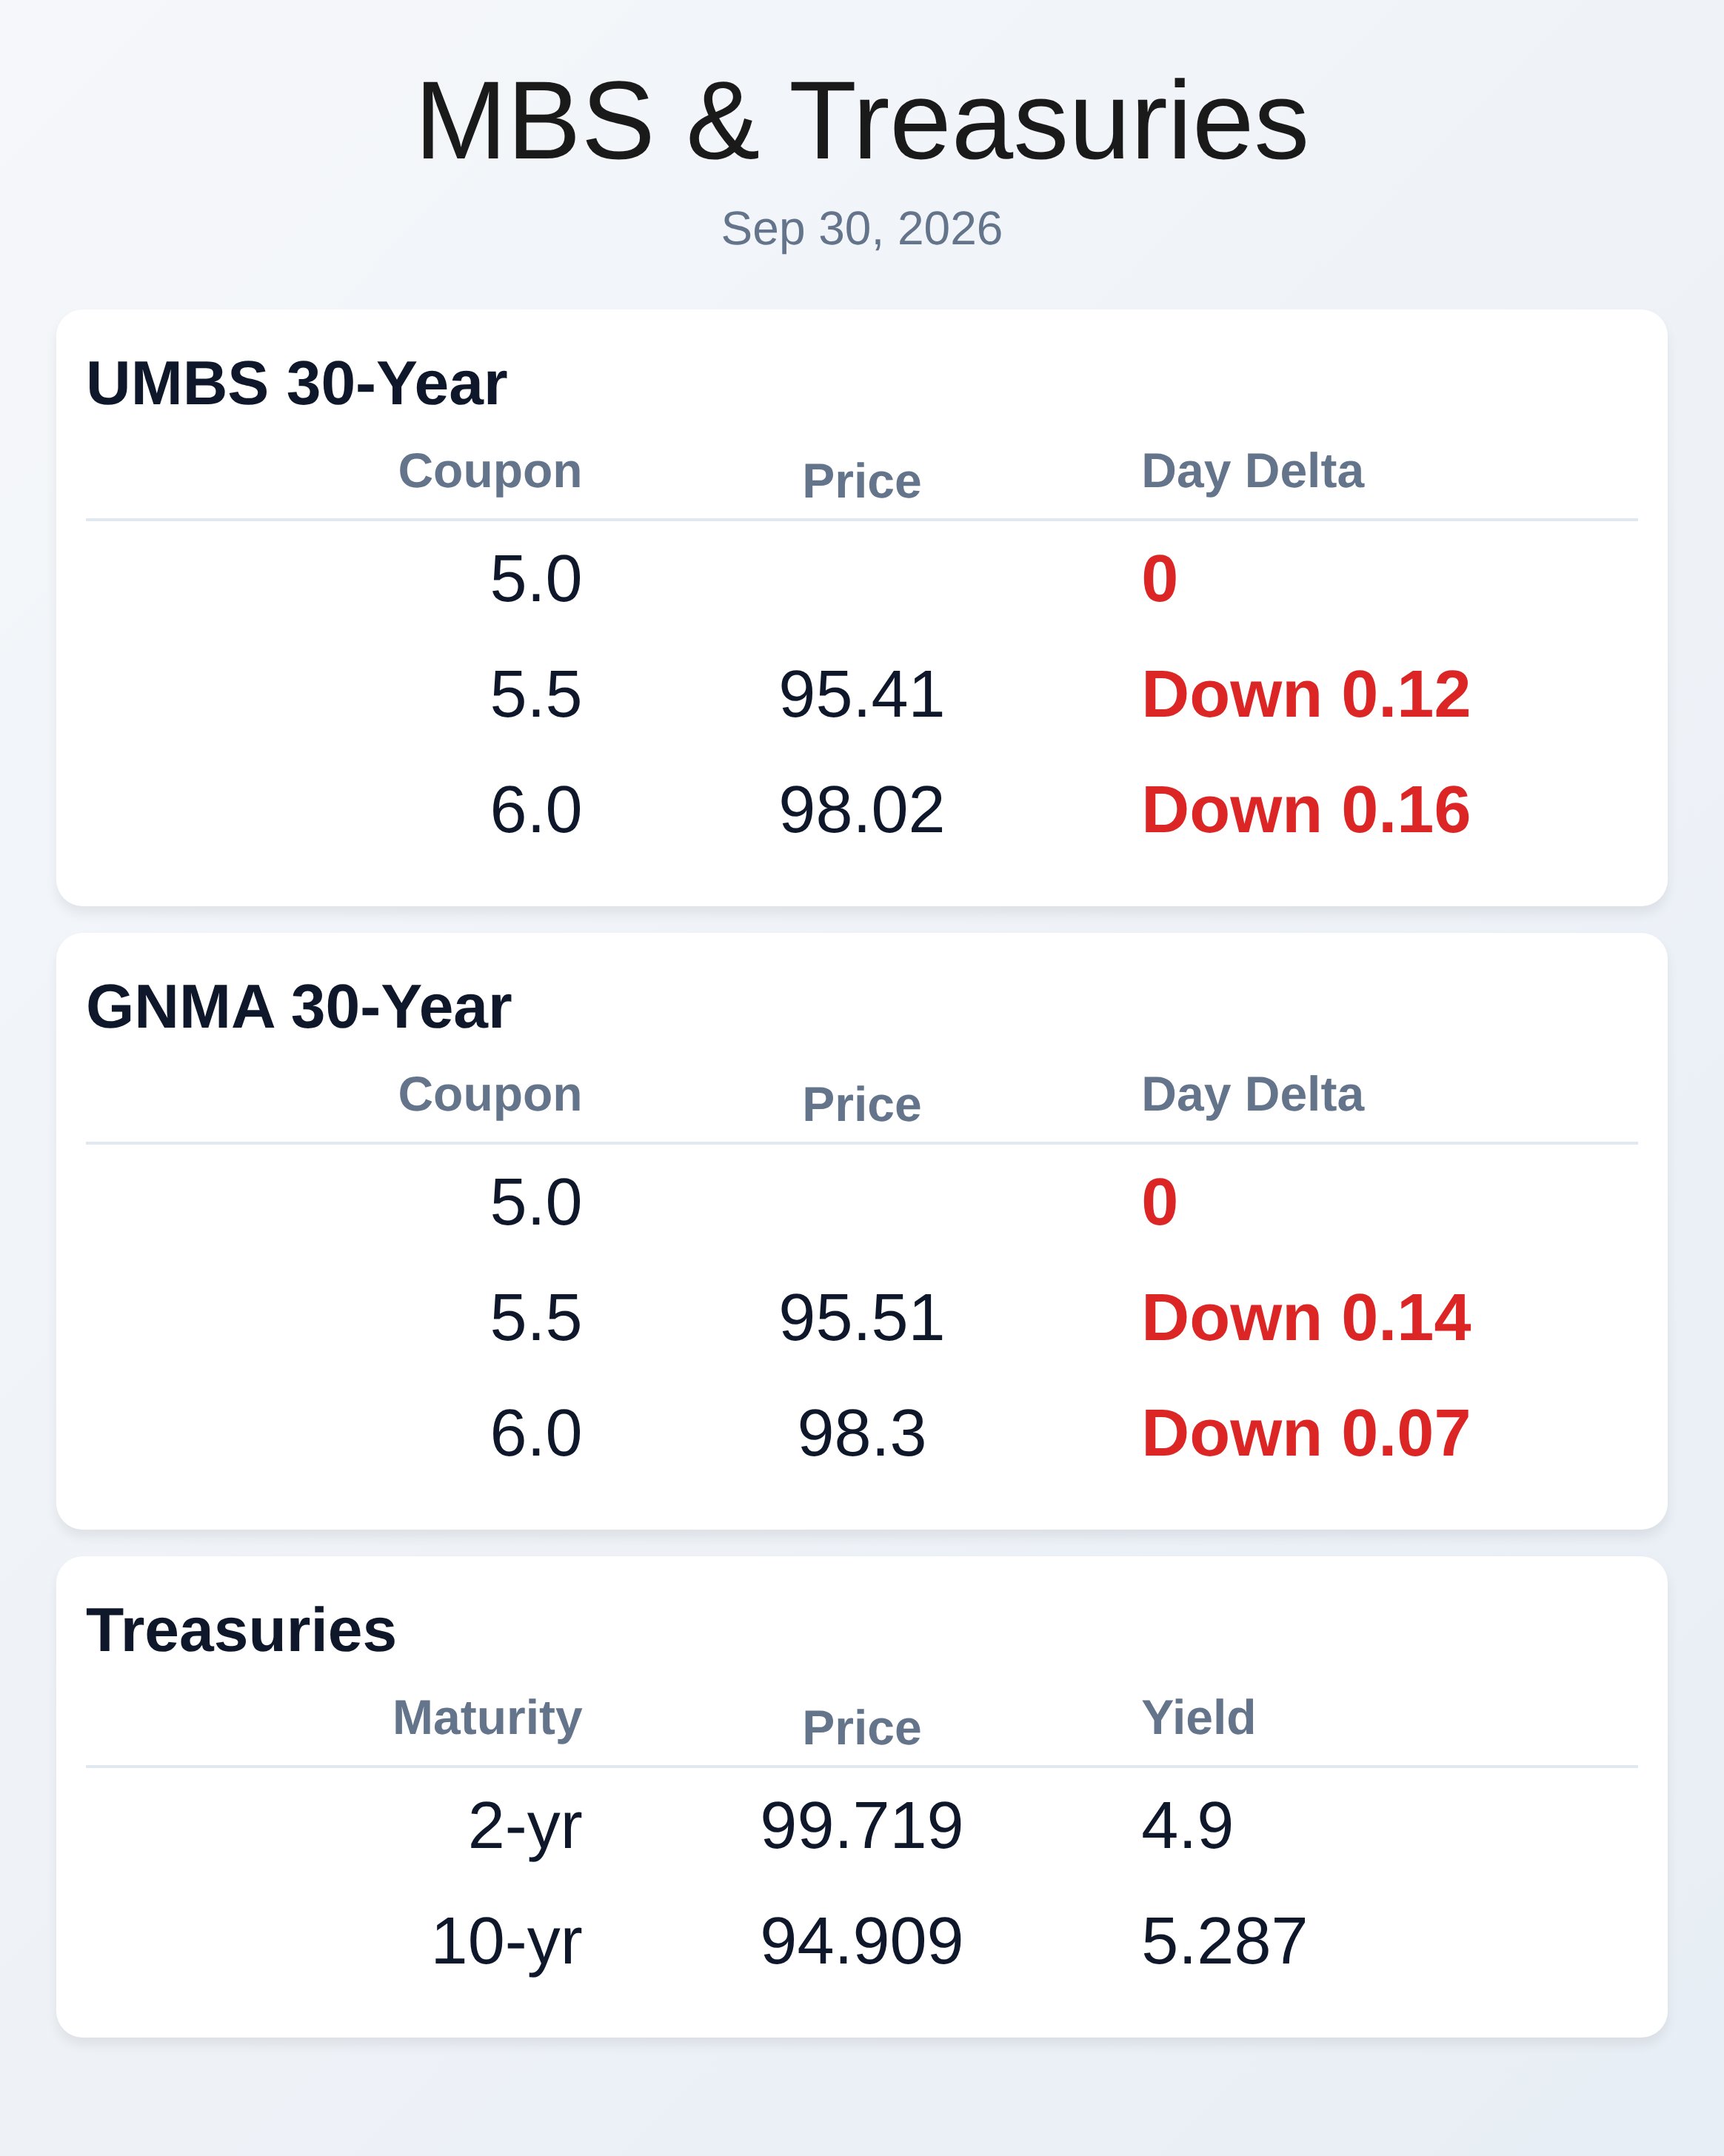
READ MORE **WTMS Blog Today = What's up in Mortgage Today (PM) - 09/30/2026** Bonds sold off sharply today without a clear catalyst, pushing 10-year Treasuries to 5.29% and forcing most lenders into reprice territory by midday. PCE inflation data came in cooler than expected this morning, but that brief rally evaporated as month-end and quarter-end dynamics took over. The MBS market moved down a quarter point from early morning rate sheet times, creating genuine pain for borrowers locked in recent days. Most mortgage originators are now weighing whether to hold the line on pricing or accept additional losses on their pipelines. Broader econ strength—GDP beat, ADP jobs higher than forecast—appears to be winning the narrative over cooling inflation. The messaging to borrowers about rate direction remains murky heading into Thursday and Friday when critical employment data hits. Month-end mechanical selling, potential portfolio rebalancing, and rumors of geopolitical escalation are layered on top of genuine economic data divergence. MBS Live analysts suggest waiting for a market rally that isn't driven by heavy selling pressure before making lock/float adjustments. If Thursday brings weak jobs or wage data, mortgage rates could stage a substantial recovery; however, stronger numbers would only reinforce today's upward momentum. Risk managers should assume reprice alerts could continue through the week. The appraisal community got a six-month reprieve today when the GSEs delayed the UAD 3.6 mandate from November 2 to May 19, 2027, giving the entire mortgage ecosystem time to catch up. The mortgage industry was sleepwalking toward compliance with less than a month remaining, and most appraisers hadn't completed even one 3.6 form. Software vendors like ACI Sky Workbench and Cotality's TOTAL had unfinished development roadmaps, while many lenders were still running legacy LOS systems incompatible with the new standard. The silver lining: business volume is weak, so appraisers have time to learn workflows without handling a crisis volume surge simultaneously. Expect the industry to use this runway more wisely than the first nine months since January's production launch. Credit scoring competition intensified today when FHFA announced Fannie Mae and Freddie Mac will now apply a single pricing grid for both Classic FICO and VantageScore 4.0 loans, eliminating the 20-point penalty that previously existed. Rocket Mortgage made VantageScore its default credit model starting Q4, having already moved 44.1% of August retail issuance to the alternative score after pulling 1.4 million dual reports. The competitive dynamic is creating meaningful borrower savings—UWM reports 25% of borrowers see better results with VantageScore, while Rocket found qualifying borrowers saved an average of $1,600 at closing. However, Fannie and Freddie's quiet disclosure of proprietary "Fannie Score" and "Freddie Score" signals that GSE-owned algorithms could eventually compete directly with FICO and VantageScore in the future. This three-way (or four-way) score competition reshapes origination economics and borrower eligibility outcomes. Thirty-year mortgage rates climbed to 7.30% this week, the highest level since November 2023, marking six consecutive weeks of increases. Total mortgage applications fell 6% as higher borrowing costs pushed purchase and refi applications down 4% and 9% respectively, with refis now 56% below year-ago levels. ARM adoption jumped to 10.3% of applications—the highest share since October 2025—as some borrowers scramble for rate relief in a higher-for-longer environment. Price cuts on listings nationwide hit 20.8%, up nearly 1 percentage point year-over-year, signaling seller capitulation. Rates continued climbing through the end of the month, reaching 7.58% by Tuesday. Mortgage originators face operational strain as Eleven Mortgage exited wholesale and correspondent lending after eight years, redirecting its parent company Benchmark's resources solely to retail. The broader organization saw producing workforce decline 32% over the past year, from 245 to 167 originators, reflecting industry contraction. Multiple wholesale lenders have quietly tightened capacity or shuttered divisions as loan volume remains depressed and competition for borrowers intensifies. Tech vendors are racing to prove value in a softer market, while the ICE Residential Whole Loan Evaluations service launched today to address secondary market pricing opacity. Originators should assume continued consolidation and channel rebalancing until application volume recovers significantly above current levels. **Locking vs Floating** MBS Live recommends waiting until the bond market shows genuine strength independent of panic selling before adjusting lock or float positioning. While cooler PCE data hints at potential Fed patience, stronger-than-expected GDP and ADP jobs readings suggest the inflation fight remains contested. Any meaningful mortgage rate recovery would likely depend on weak employment reports arriving Thursday or Friday; conversely, strong labor data would likely accelerate the recent upward momentum in rates. **Today's Events** ADP jobs (September): 90K versus 70K forecast, 38K previous Core PCE (month-over-month, August): 0.2% versus 0.3% forecast, 0.2% previous Core PCE (year-over-year, August): 3.0% versus 3.3% forecast, 3.3% previous Core PCE Prices (quarter-over-quarter, Q2): 3.30% versus 3.6% forecast, 4.4% previous Corporate profits (Q2): 7.7% versus 8.2% forecast, 0.5% previous GDP (Q2): 2.2% versus 1.5% forecast, 2.1% previous GDP Final Sales (Q2): 2.8% versus 2.2% forecast, 1.9% previous PCE (year-over-year, August): 3.4% versus 3.7% forecast, 3.7% previous PCE prices (month-over-month, August): 0.3% versus 0.4% forecast, 0.2% previous **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | | 5.5 | 95.41 | -0.12 | | 6.0 | 98.02 | -0.16 | | 5.5 | 95.51 | -0.14 | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | | 2yr | 4.9 | 99.719 | 0.023 | | 3yr | 5.001 | 98.275 | 0.031 | | 5yr | 5.093 | 99.596 | 0.046 | | 7yr | 5.188 | 98.906 | 0.049 | | 10yr | 5.287 | 94.909 | 0.055 | | 30yr | 5.632 | 92.698 | 0.067 | Market Data
Mortgage Today (AM) - 09/30/26 {{catlist}}
September 30, 2026
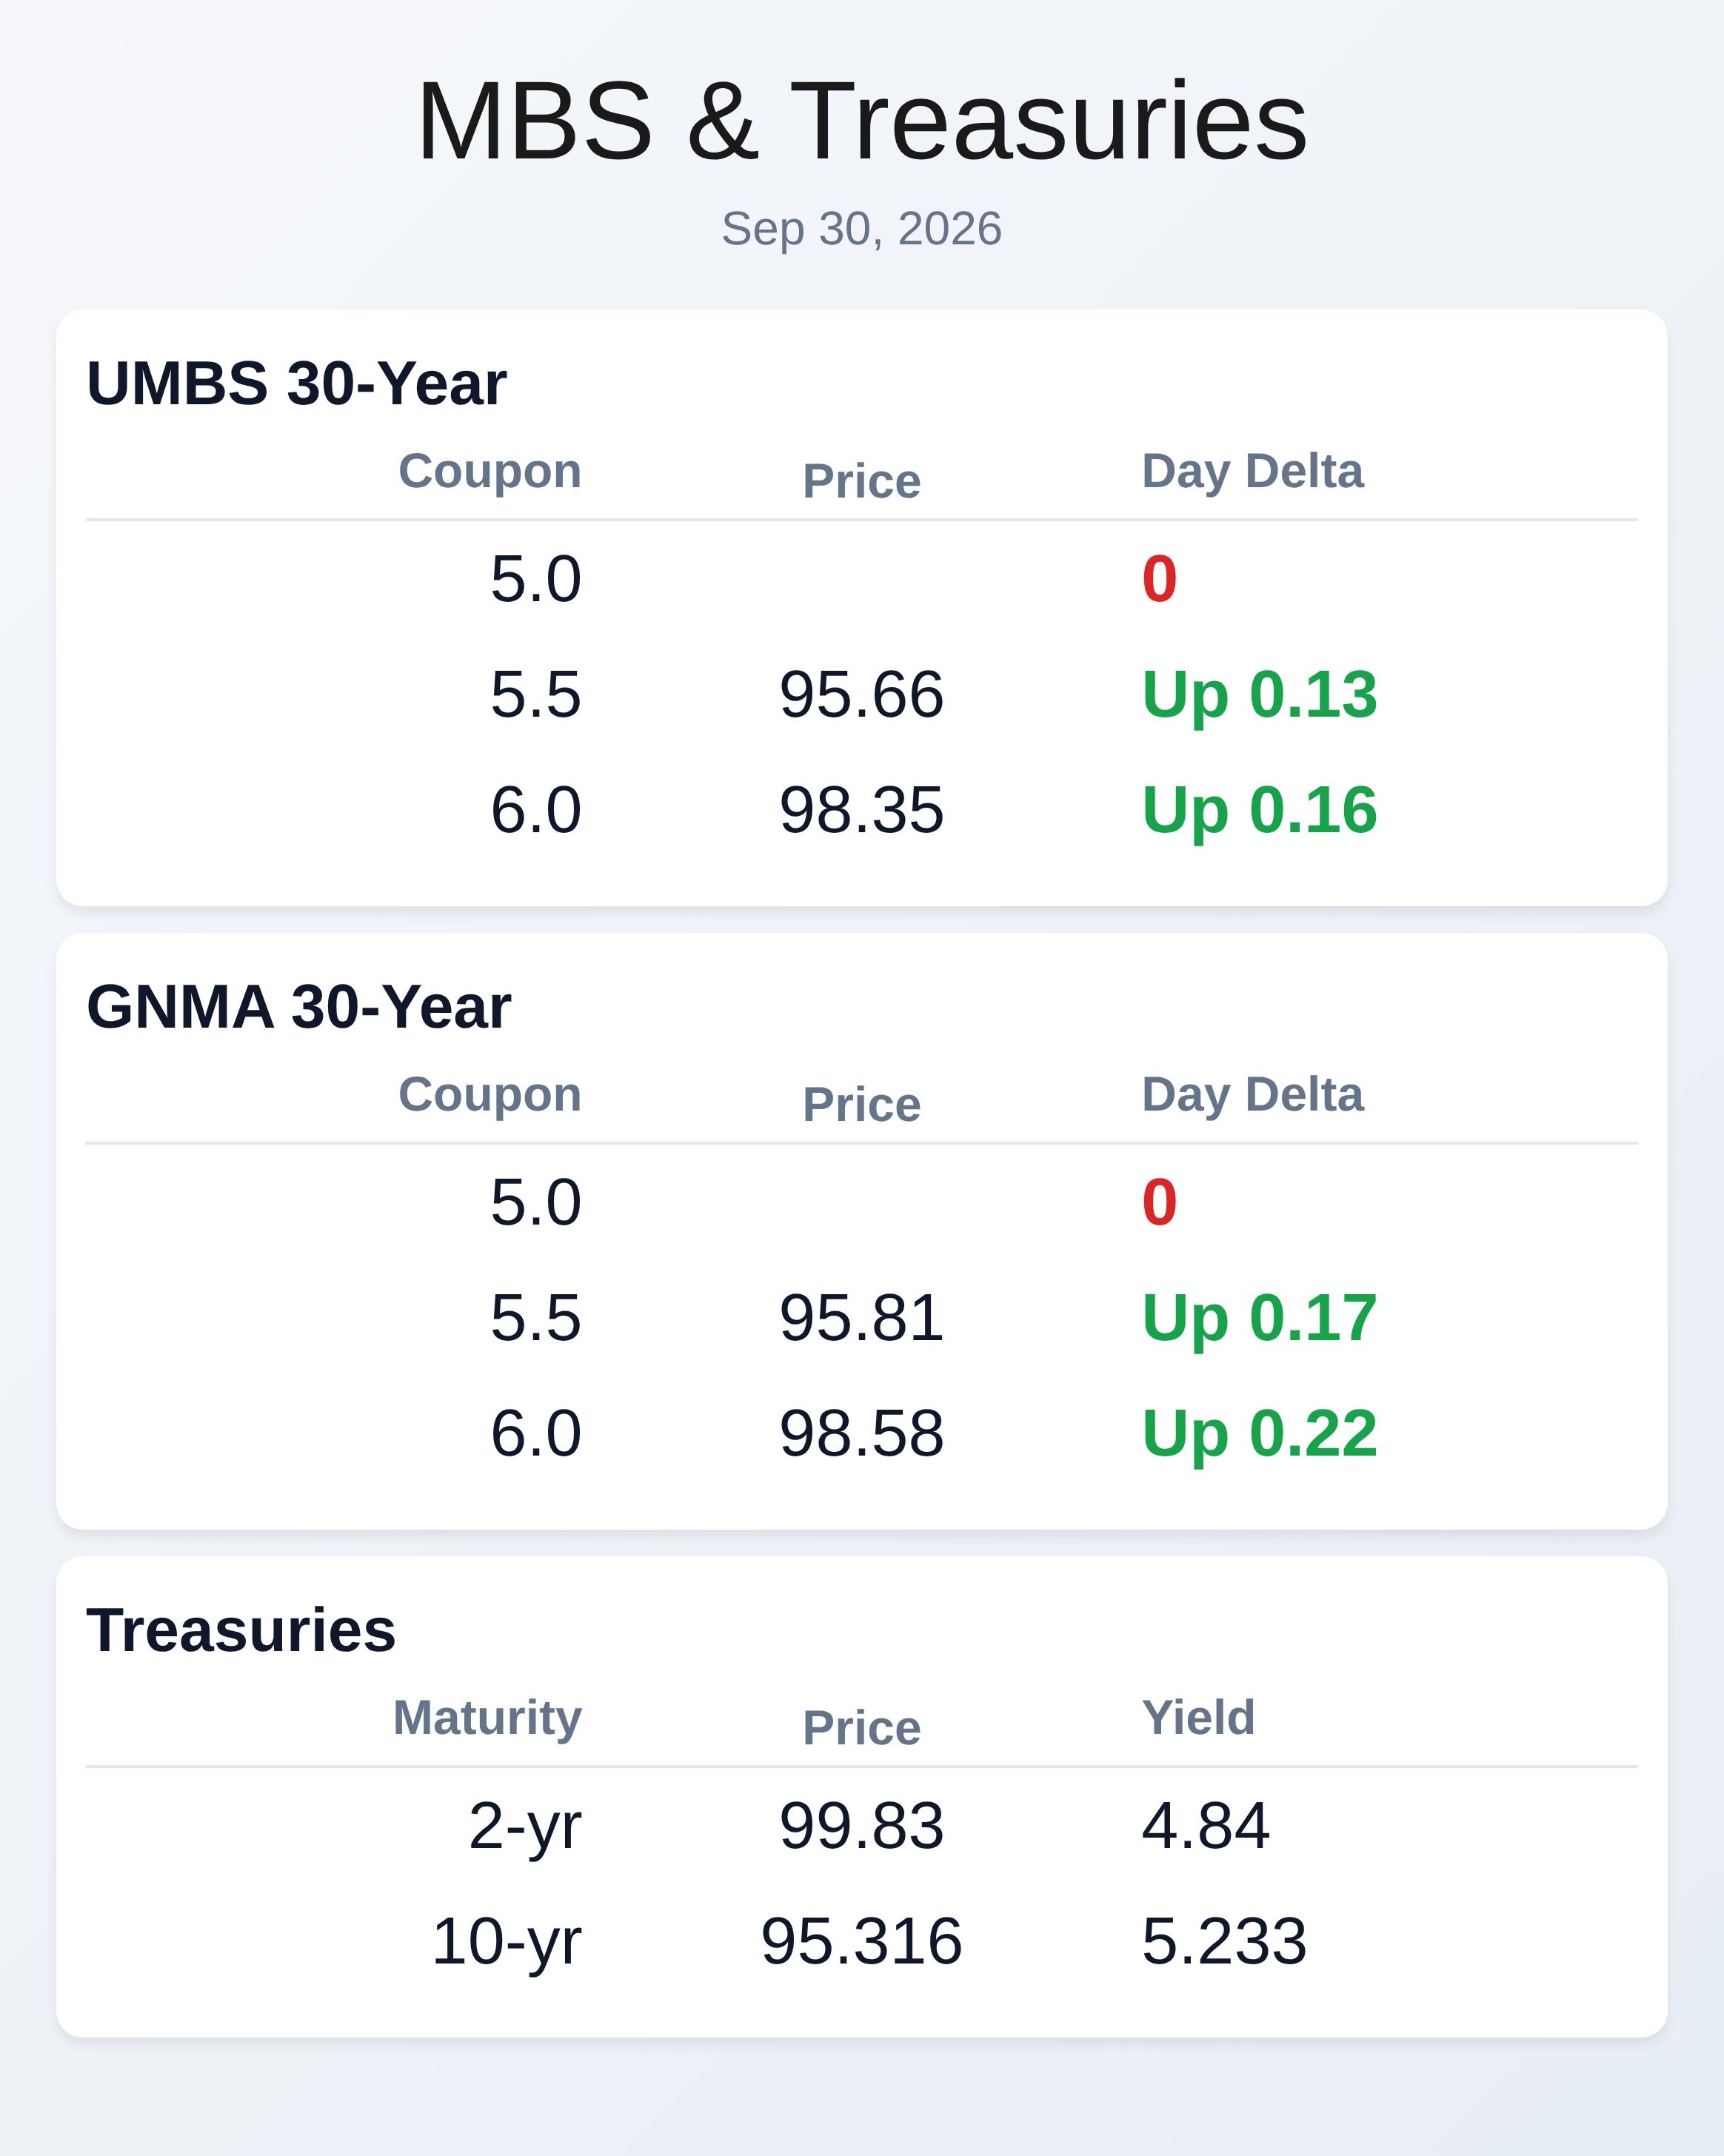
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/30/2026** Mortgage applications plummeted 6 percent in the week ending September 25, with refinancing down a staggering 56 percent year-over-year as rates climbed to three-year highs. Purchase applications declined 4 percent seasonally adjusted and 14 percent annually, signaling that borrowers are stepping back from the market entirely. The pullback reflects the brutal impact of elevated borrowing costs, which have now pushed long-term yields to levels unseen since 2002. Yesterday's 10-year Treasury closed at 5.26 percent, and the 30-year hit 5.62 percent as the bond market sold off despite weaker economic data. MBS securities lost roughly 25 basis points in the move. This morning brought a mixed inflation picture that sparked a modest intraday relief rally. The August Core PCE price index came in cooler than expected at 0.2 percent month-over-month (versus 0.3 percent forecast) and 3.0 percent year-over-year (versus 3.3 percent forecast). Personal spending rose 0.6 percent inflation-adjusted in August, marking the fastest pace in over a year, while ADP employment climbed 90,000 jobs—beating the 70,000 forecast. Q2 GDP printed at 2.2 percent, topping the 1.5 percent estimate, which suggests the economy remains resilient despite mortgage headwinds. By mid-morning, the 10-year Treasury had pulled back three basis points to 5.20 percent and UMBS securities posted modest intraday gains. Fed officials struck a cautious tone overnight, with President Williams stating there is no urgency for additional rate hikes after September's move and that policymakers should gather more information. Governor Barr emphasized recalibrating policy to balance employment and inflation risks while returning inflation to 2 percent in a timely manner. The message sent traders into bond-buying mode early in the session, though analysts warned that the relief could prove temporary. Without clear evidence of economic deterioration or a meaningful shift in the Fed's inflation outlook, dip-buying has lacked sustained conviction. The market remains technically oversold and awaiting more concrete catalysts from Wednesday's PCE data and Friday's official payrolls report. The capital markets are struggling with a fundamental disconnect: economic data shows resilience, yet the bond market keeps selling off long-dated maturities. Heavy corporate issuance is hitting the tape, with jumbo tranches scheduled for pricing today that will add supply pressure. Convexity hedging, positioning concerns, and persistent worries over federal borrowing and inflation have dominated the long end of the curve. The 2-year-to-10-year curve steepened to 37 basis points yesterday, a move that underscores yield volatility. Originators and lenders are now operating in an environment where mortgage rates have disconnected from near-term Fed policy and are instead driven by structural forces in the Treasury market. Mortgage professionals face a critical decision window in October. Lock-float recommendations from market analysts suggest waiting until bonds demonstrate a stronger desire to rally without that rally being purely a reaction to heavy selling pressure. The economic calendar remains crowded with potential volatility triggers, and borrowers who held off in September are unlikely to re-enter the market quickly at current rate levels. Portfolio lenders and warehouse lines are under pressure as refi demand evaporates and purchase applications decline. For originators, the focus must shift from volume preservation to pricing discipline and cultivating relationships with existing clients who might refinance in a lower-rate environment. **Locking vs Floating** The data backdrop supports a wait-and-see posture on rate locks. While inflation showed modest improvement this morning, the bond market's broader trajectory remains firmly upward on yield, driven by supply and structural factors beyond the Fed's near-term control. Only concrete signs of economic weakness or a meaningful repricing of inflation risk would justify an aggressive pivot to locking. Borrowers and originators should monitor Friday's employment report closely, as a significant miss to the downside could finally break the bond selloff momentum. **Today's Events** ADP Employment Change (8:15 AM): +90K vs. +70K forecast, +38K previous Core PCE (month-over-month, August): +0.2% vs. +0.3% forecast, +0.2% previous Core PCE (year-over-year, August): +3.0% vs. +3.3% forecast, +3.3% previous PCE Price Index (month-over-month, August): +0.3% vs. +0.4% forecast PCE Price Index (year-over-year, August): +3.4% vs. +3.7% forecast Q2 GDP (third estimate): +2.2% vs. +1.5% forecast, +2.1% previous Q2 Final Sales: +2.8% vs. +2.2% forecast Q2 Corporate Profits: +7.7% vs. +8.2% forecast Chicago PMI (September): Pending, 9:45 AM EDT Fed Speakers: Governor Cook (3:25 PM), Chicago Fed President Goolsbee (5:10 PM), Minneapolis Fed President Kashkari (later in day) **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | | 2 yr | 4.84 | 99.83 | -0.036 | | 3 yr | 4.939 | 98.446 | -0.039 | | 5 yr | 5.025 | 99.891 | -0.025 | | 7 yr | 5.129 | 99.25 | -0.014 | | 10 yr | 5.233 | 95.316 | -0.012 | Market Data
LATEST ARTICLES

RECENT ARTICLES

31 Laws – Last 6

April 6th, 2023|Money|

Reading Notes for: Peter Diamandis’ 32 Laws 26.  Without a target you’ll miss it every time. If you don’t know where you are going, it’s very hard to get there. [...]

Article Archive

Subscribe

Send me some brain food

Go to Top