Loading...
HOME2023-01-22T13:43:33-07:00

Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.

I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.

I still remember how it started for me. It started in June of 2008. After 11  years …..Click to continue

Mortgage Today (PM) - 09/23/26 {{catlist}}
September 23, 2026
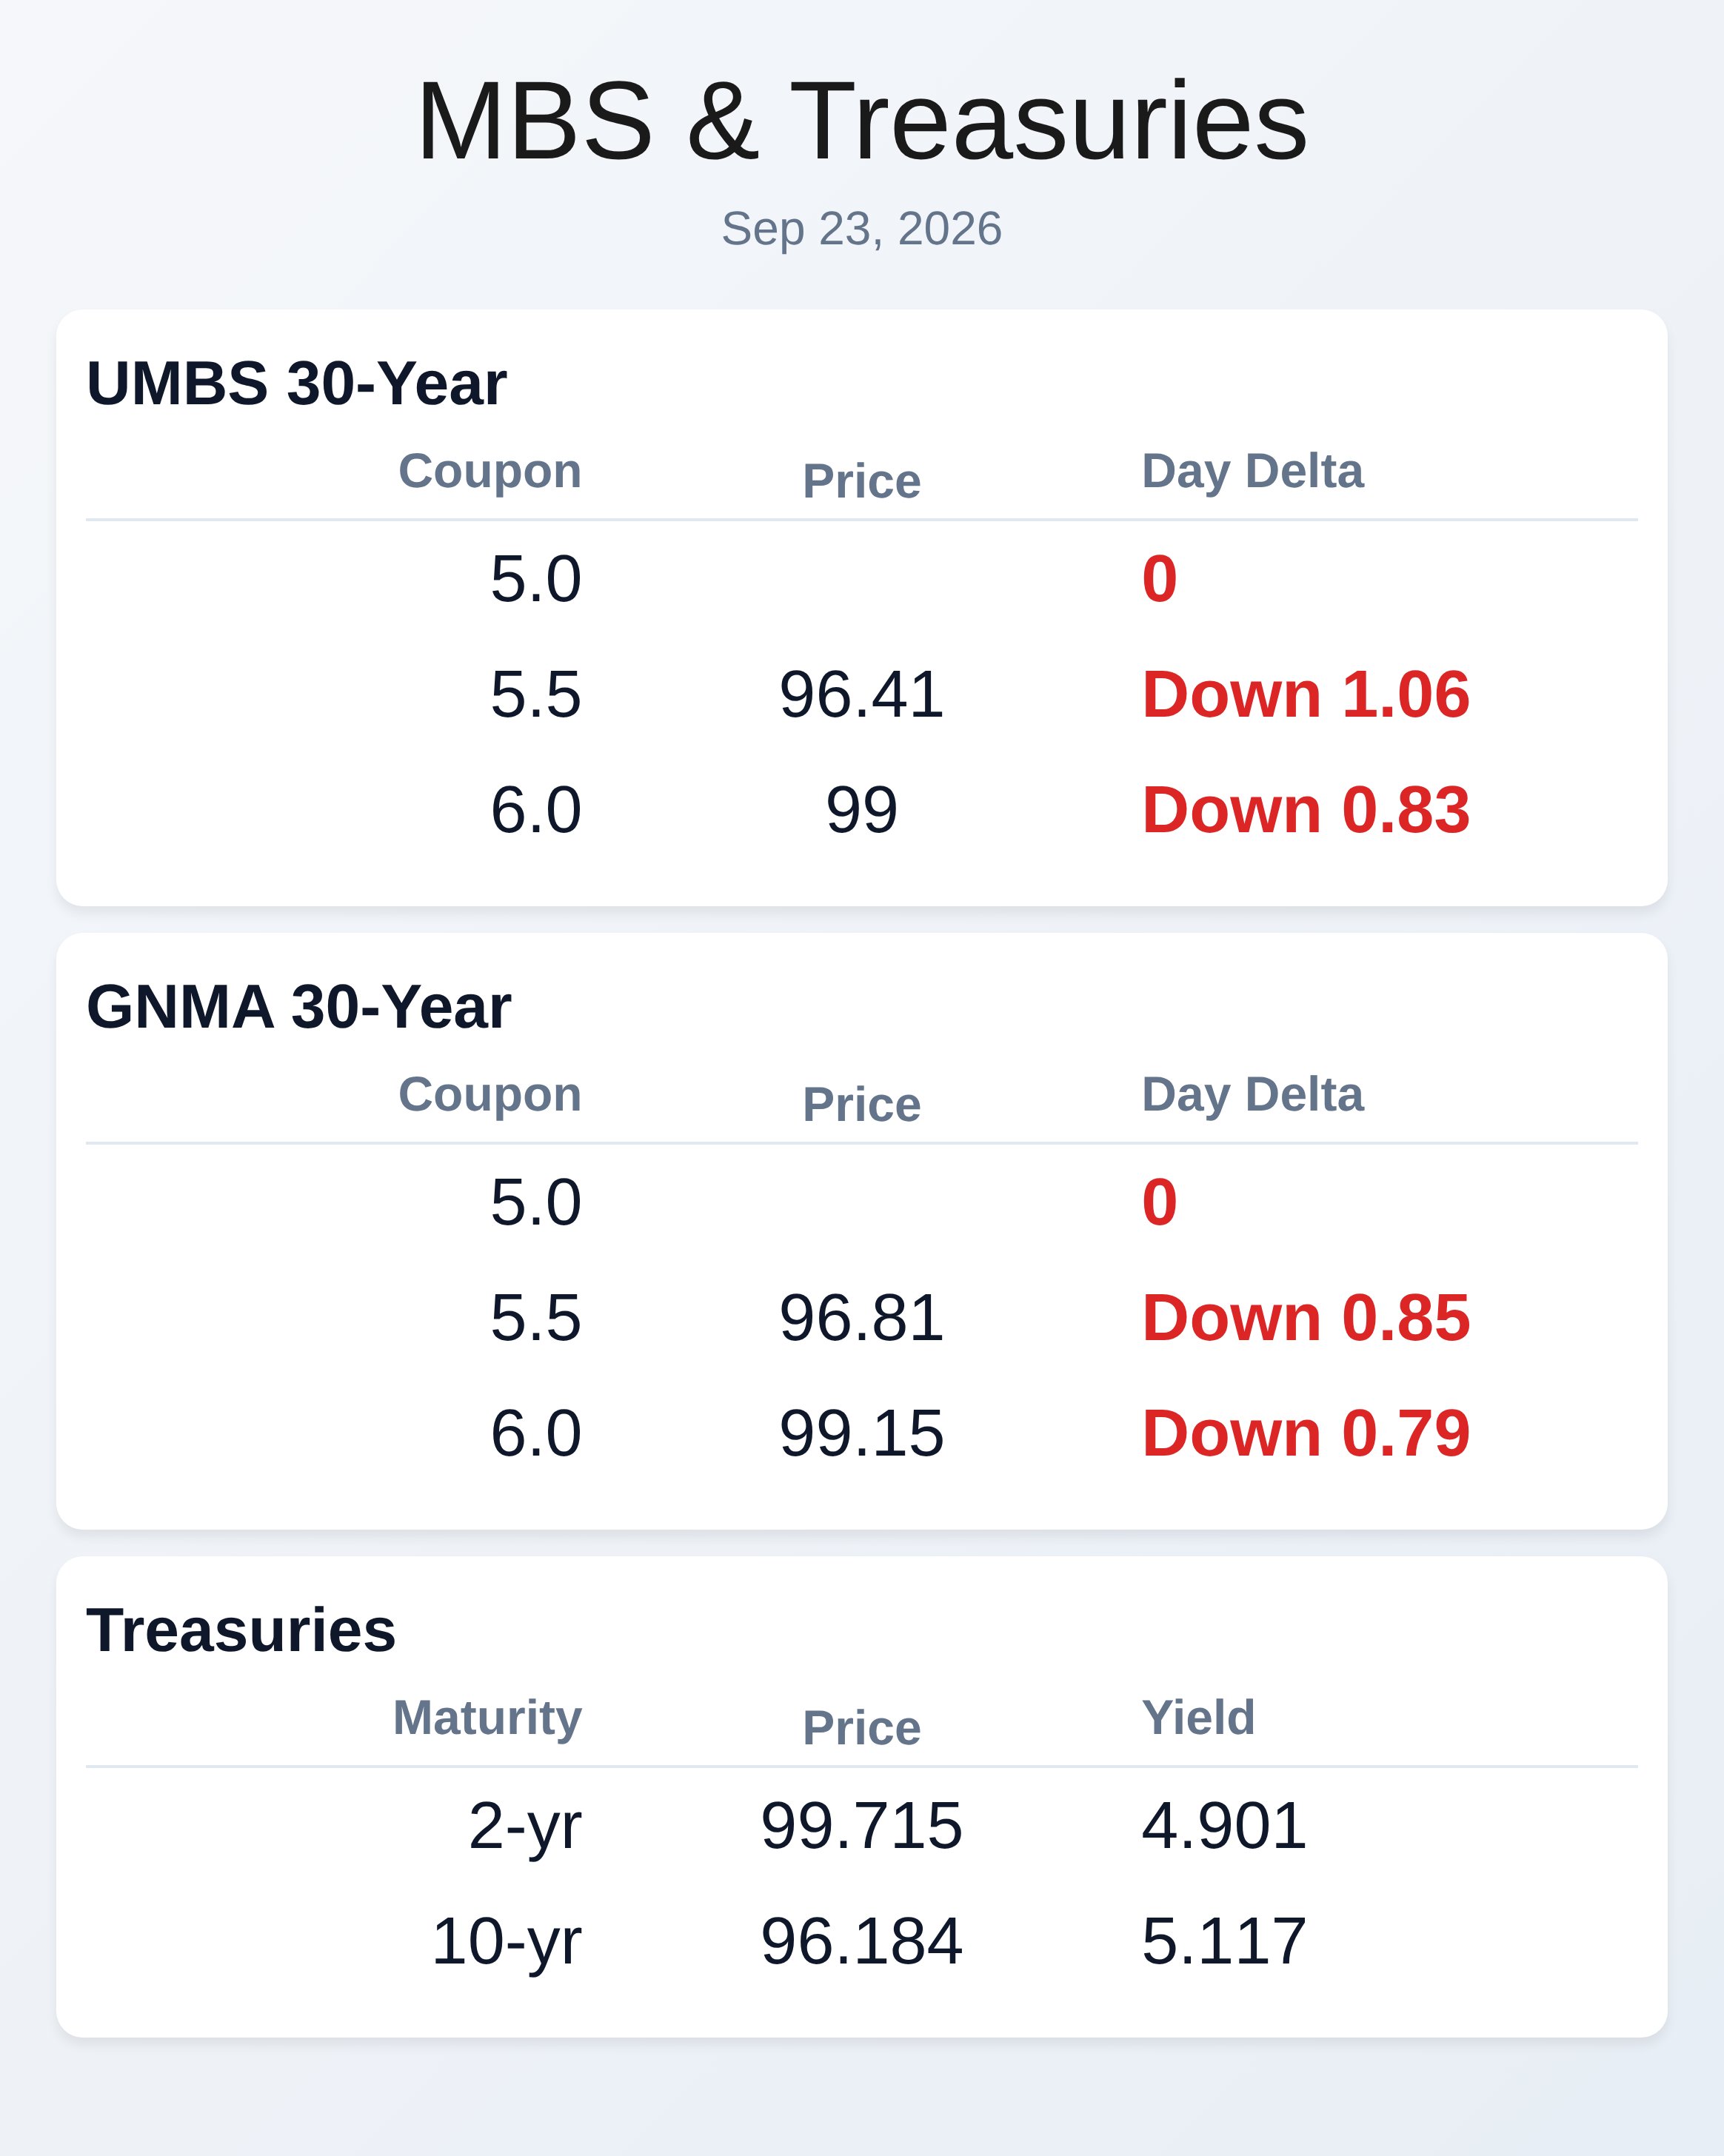
READ MORE **WTMS Blog Today = What's up in Mortgage Today (PM) - 09/23/2026** UMBS securities tanked more than half a point today as surprisingly strong economic data pushed Treasury yields to their highest levels since 2007, signaling the Fed has room for additional rate hikes. The S&P Global PMI data hit multi-year highs across both manufacturing and services, triggering immediate bond selling and forcing lenders to reprice rate sheets downward. Ten-year Treasury yields jumped from 5.0% to over 5.04%, with market pricing showing over 50% odds for a second rate hike at the next Federal Reserve meeting. MBS are down approximately 56 basis points on the day, leaving many lenders scrambling with negative reprices before borrowers see updated rates. This kind of volatility creates urgency for borrowers sitting on the fence to lock rather than float. The mortgage origination business faces a structural problem that has little to do with whether rates are 7% or 6%. According to analysis from The Mortgage Scoop, the industry is producing roughly half as many loans today compared to the late 1990s when rates were similarly elevated, yet average loan balances have grown 53% since 2015 while production expenses exploded. Loan officer compensation has remained indexed to loan balance at roughly 100 basis points, meaning a $400,000 mortgage pays twice what a $250,000 mortgage does, even though the work required is nearly identical. When production revenue per loan dropped from 434 basis points in 2020 to 333 basis points in Q2 2026, that same $4,000 LO commission suddenly represented 30% of lender revenue instead of 23%. Originators now need roughly 1,515 loans annually to generate the same $1.19 million in production profit that 1,000 loans produced in 2015. The compensation model created after the 2008 crisis to eliminate conflicts of interest has ironically become a new pressure point as markets tighten. When loan amount became the index for LO pay, it worked because rates were falling and home values were surging, so bigger loan balances correlated with bigger lender revenues. Today's environment inverts that equation—lenders must chase more volume with shrinking margins while loan officers still expect their balance-based commissions. This mismatch explains why even "historical" rate levels feel desperate to the industry; the business model supporting those rates depends on either massive volume or massive margins, and borrowers are not materializing regardless of messaging about historically normal rates. Freddie Mac's mortgage-backed securities buying could help compress spreads by another 10 to 12 basis points, according to the Community Home Lenders of America, though that relief depends on Treasury yields cooperating. The FHFA disclosed last week that Fannie and Freddie were ramping up large-quantity MBS purchases after three consecutive months of declining holdings. Even 12 basis points of spread compression would matter to originators grinding through lower profitability, but Treasury yields can easily move in the opposite direction and erase any gains from secondary market support. The real question for mortgage sellers is whether policy support translates to rate sheet improvement or simply prevents spreads from blowing wider. Loan officers may be underestimating borrower demand for digital closing technology, according to new ServiceLink research highlighting a disconnect between originator assumptions and consumer expectations. Many borrowers want streamlined digital experiences, yet lenders continue deploying traditional paper-based processes or half-measures that frustrate both parties. UWM's new Underwriting+ platform combines underwriting, processing, and borrower communication into a single workflow, with pilot loans averaging just 8.3 days from submission to clear-to-close. This kind of technology adoption becomes even more critical when originators must close more volume with fewer staff and tighter economics. Mutual of Omaha's mortgage division auction caught even internal stakeholders by surprise, signaling potential consolidation in a market already under pressure from rate volatility and volume constraints. The broader mortgage industry faces a test of resilience as borrower demand remains soft at 4.5% to 4.6% rate levels, production margins compress further, and compensation models designed for a different era strain lender profitability. Companies that cannot adapt their cost structures or technology infrastructure risk becoming acquisition targets or casualties. **Locking vs Floating** With the 10-year Treasury at 5.06% and strong economic data supporting further Fed rate hikes, borrowers with closings approaching should strongly favor locking rates. Treasury yields are at their highest since 2007, and market pricing suggests additional rate increases are likely, making floating a high-risk bet for near-term closings. **Today's Events** September 23, 2026: MBA Mortgage Market Index (230.8 forecast), MBA Purchase Index (156.2 forecast), S&P Global Composite PMI (56 forecast), S&P Global Manufacturing PMI (53.6 forecast), S&P Global Services PMI (56 forecast), 5-Year Note Auction. **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | Market Data
Mortgage Today (AM) - 09/23/26 {{catlist}}
September 23, 2026
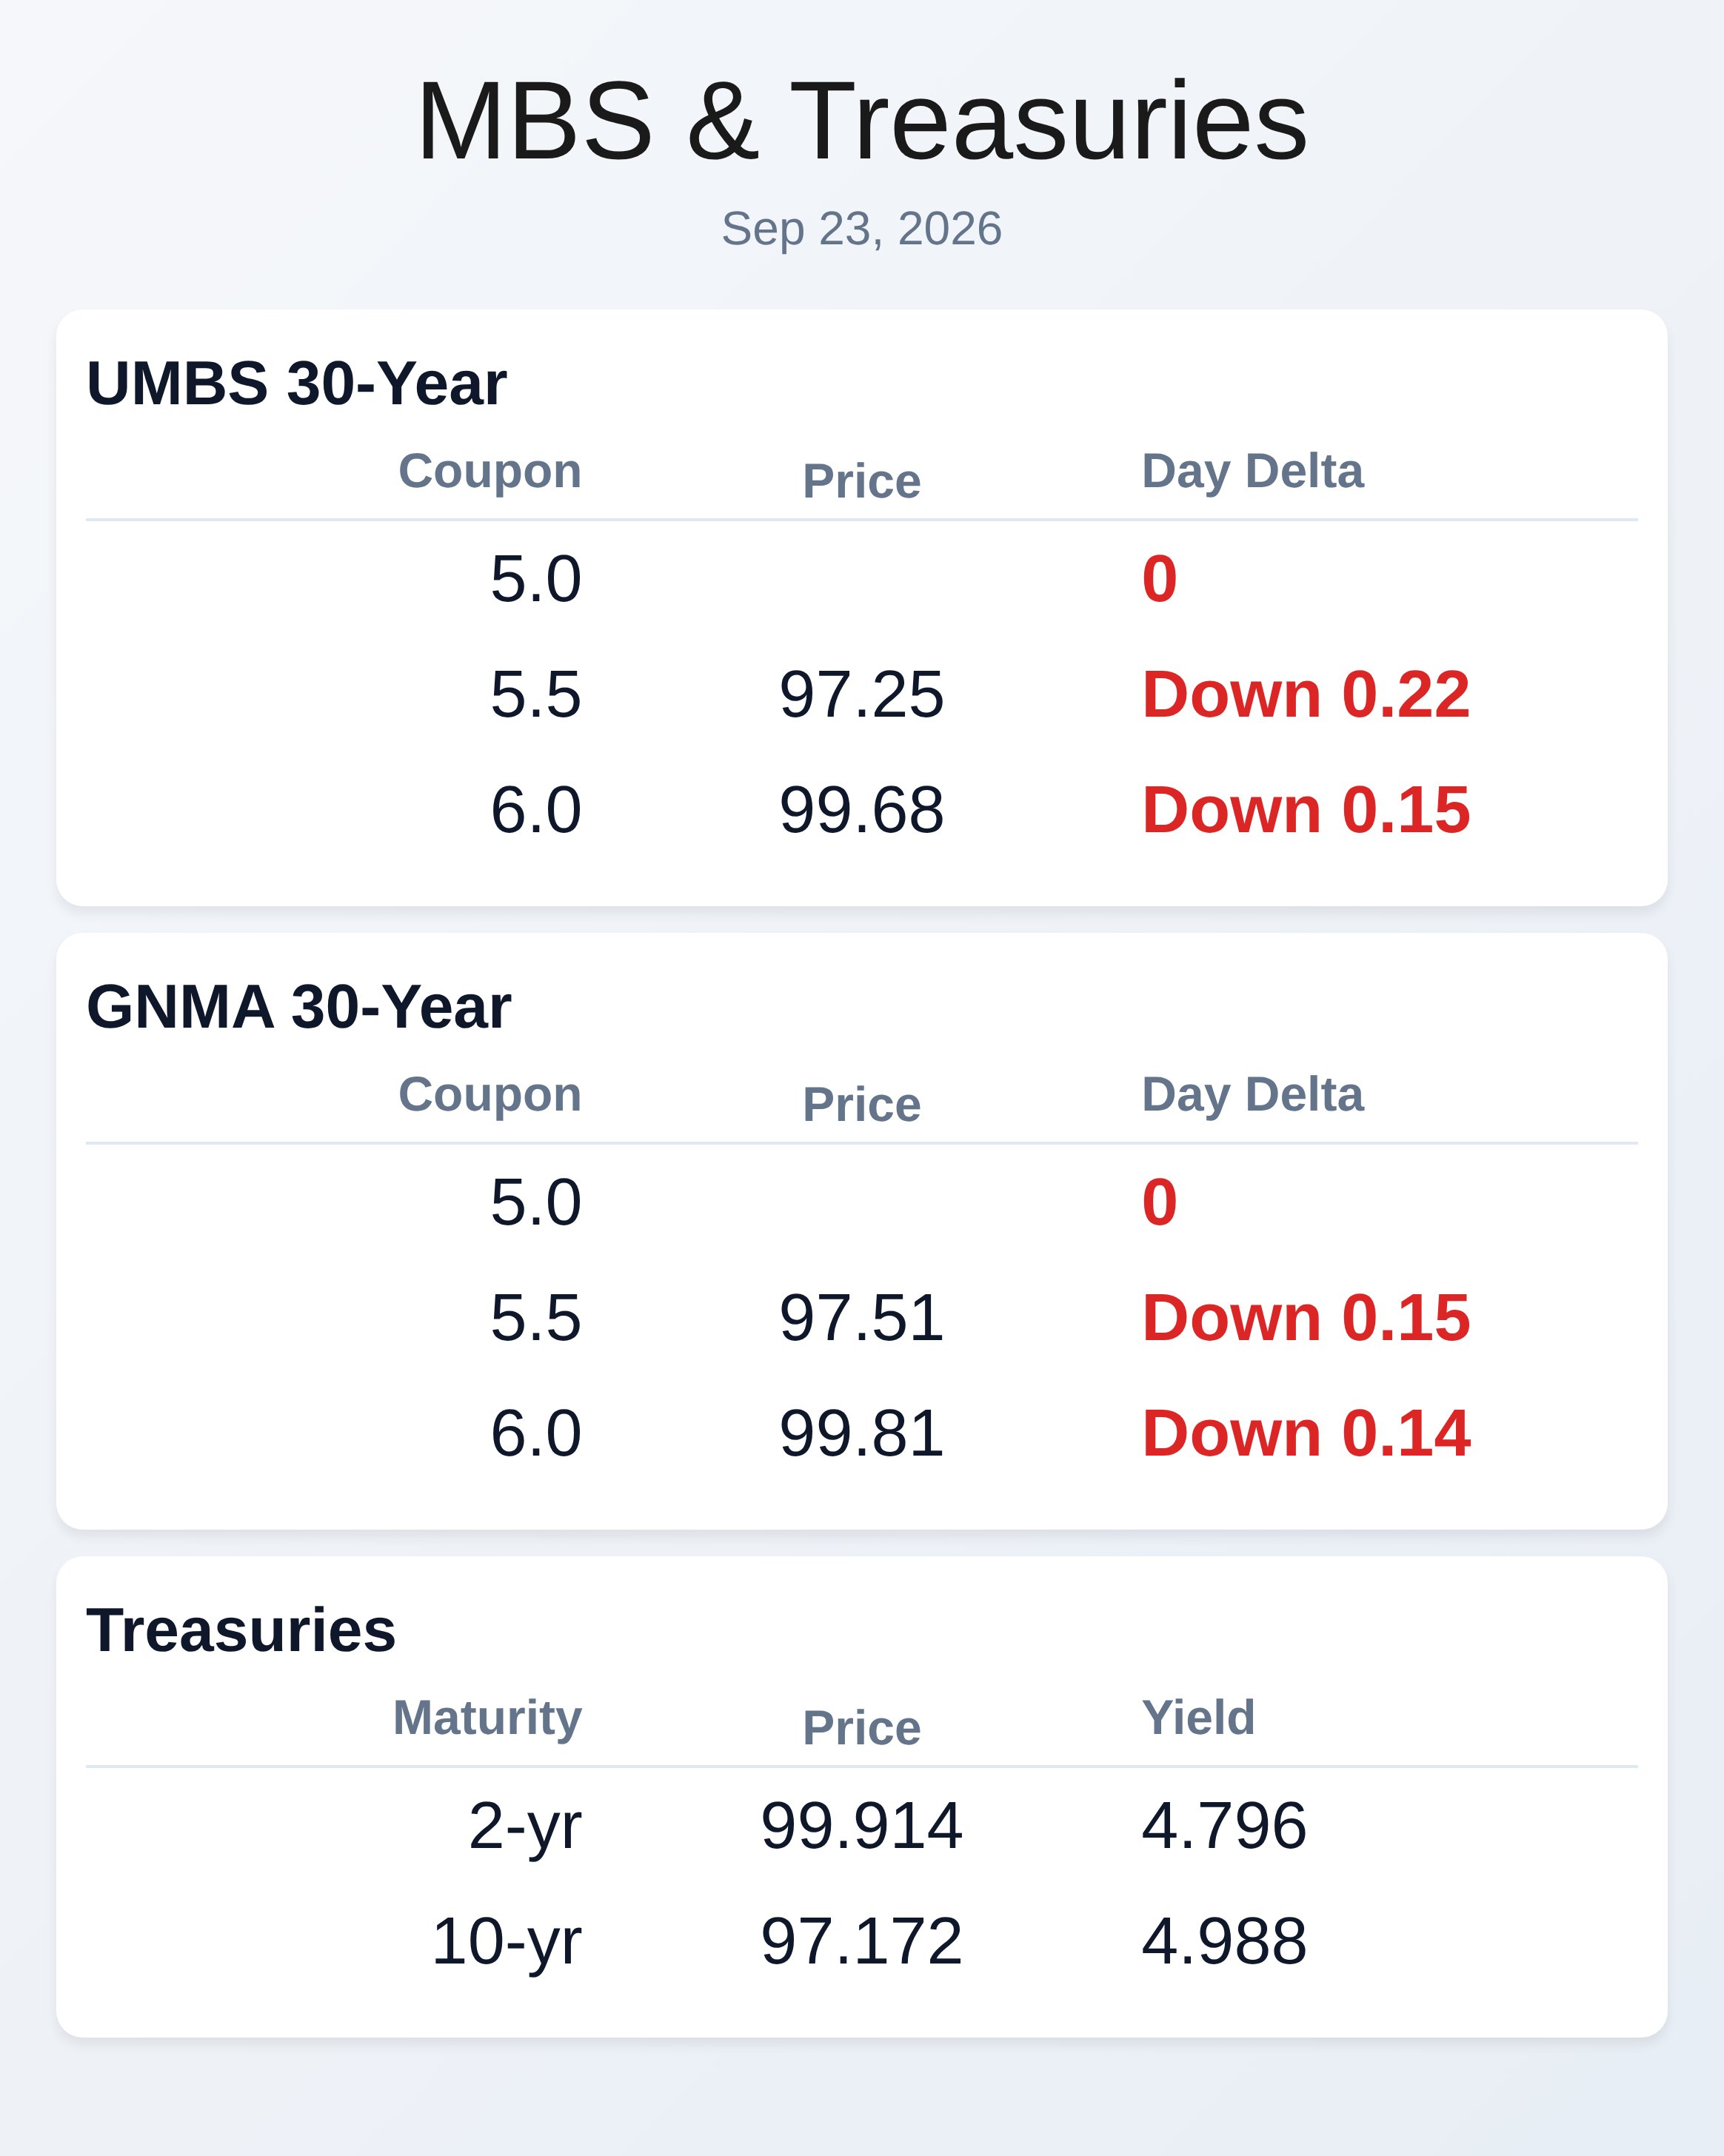
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/23/2026** Mortgage rates surged to 7.12% last week, the highest level since 2024, forcing application volume down 1.5% and pushing nearly one in ten borrowers toward adjustable-rate mortgages. Refinance activity collapsed to its lowest level since February 2025, with refi applications down 62% year-over-year. The 30-year fixed is now more than a percentage point above ARM rates, making the exotic product suddenly attractive during this affordability crisis. Purchase applications slipped just 1% week-over-week but remain 11% lower than last year. As the fall market officially begins, real estate agents are already reporting a sharp pullback from prospective buyers. War headlines and oil price volatility are dominating bond market attention, with geopolitical uncertainty creating daily swings that overwhelm economic data. Late yesterday, reports of productive U.S.-Iran negotiations temporarily stabilized Treasuries and helped the market absorb a $69 billion 2-year note auction. The 10-year Treasury sits at 4.988%, while Agency MBS prices remain little changed from yesterday's close. Without a clear catalyst for rate relief, the structural deficit and persistent oil concerns should keep upward pressure on long-end yields. The Fed's public silence on skyrocketing fiscal spending contrasts sharply with its aggressive stance on inflation tied largely to crude oil pricing. Homebuilders are increasingly dependent on FHA-financed buyers to move volume during this cyclical slowdown. Ashton Woods has seen FHA-financed sales surge from 15% of total transactions in 2022 to 39% today. This trend reflects broader affordability pressures squeezing move-up buyers out of traditional markets. The shift demonstrates how housing affordability deterioration is forcing both lenders and builders to lean more heavily on government-backed programs. KB Homes warned in earnings that market conditions have weakened significantly since June, with higher rates and buyer hesitation dampening demand. Fannie Mae is tightening documentation requirements for investors converting homes into rentals, eliminating lease agreements as acceptable proof of rental income effective November 1. Lenders must now use appraisals, Form 1007, or comparable market data from sources like Zillow or MLS with three recent comps. Move-up buyers benefit because they no longer need an existing tenant before applying, though the qualifying math remains unchanged with a 25% reduction for vacancy and expenses. Freddie Mac maintains a more flexible approach, still accepting leases and refusing market-analysis tools. Lenders must verify which GSE they're delivering to before presenting rental income strategies to borrowers. A bipartisan proposal would provide up to $50,000 in down payment assistance to first-time homebuyers, addressing the affordability crisis gripping the market. The legislation represents a direct response to the mounting pressure consumers face as rates hover near 7% and median home prices remain historically elevated. Zillow faces a new legal challenge seeking to dismiss a RESPA lawsuit accusing the platform of steering borrowers to its in-house mortgage business through its real estate referral program. The court has already rejected two previous versions of the complaint, and Zillow is now pushing for permanent dismissal with prejudice. Pending home sales edged up just 0.3% in August, suggesting buyer activity remains tepid despite seasonal expectations. UAD 3.6 appraisal format changes are driving costs higher as appraisers navigate expanded inspection requirements and extended reporting timelines. Class Valuation's analysis shows appraisers already charging premium fees due to the added labor and time demands of the new standards. Hybrid appraisals that meet UAD 3.6 data capture standards offer lenders faster turnarounds and lower pricing, making them increasingly attractive as traditional appraisal fees climb week-to-week. Lenders should disclose longer appraisal timelines now and prepare borrowers for extended underwriting schedules over the next 90 days. Ignoring hybrid appraisal options during this transition period could cost originators both time and revenue as conventional processing delays mount. **Locking vs Floating** War and oil volatility are controlling daily bond moves without creating a directional bias. Technical levels remain relevant between 4.93% and 5.01% on the 10-year, so traders should wait for a definitive break outside this range before shifting lock-float strategy. The default conservative stance established in July remains unchanged—originators should maintain cautious locking discipline until a clear rally develops in bond pricing. **Today's Events** Fed Governor Barr remarks, preliminary S&P Global Manufacturing PMI, Services PMI, crude oil inventory reports, and a $70 billion 5-year Treasury note auction are scheduled for later today. **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | | 5.5 | 97.25 | -0.22 | | 6.0 | 99.68 | -0.15 | | 5.5 | 97.51 | -0.15 | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | Market Data
Mortgage Today (PM) - 09/22/26 {{catlist}}
September 22, 2026
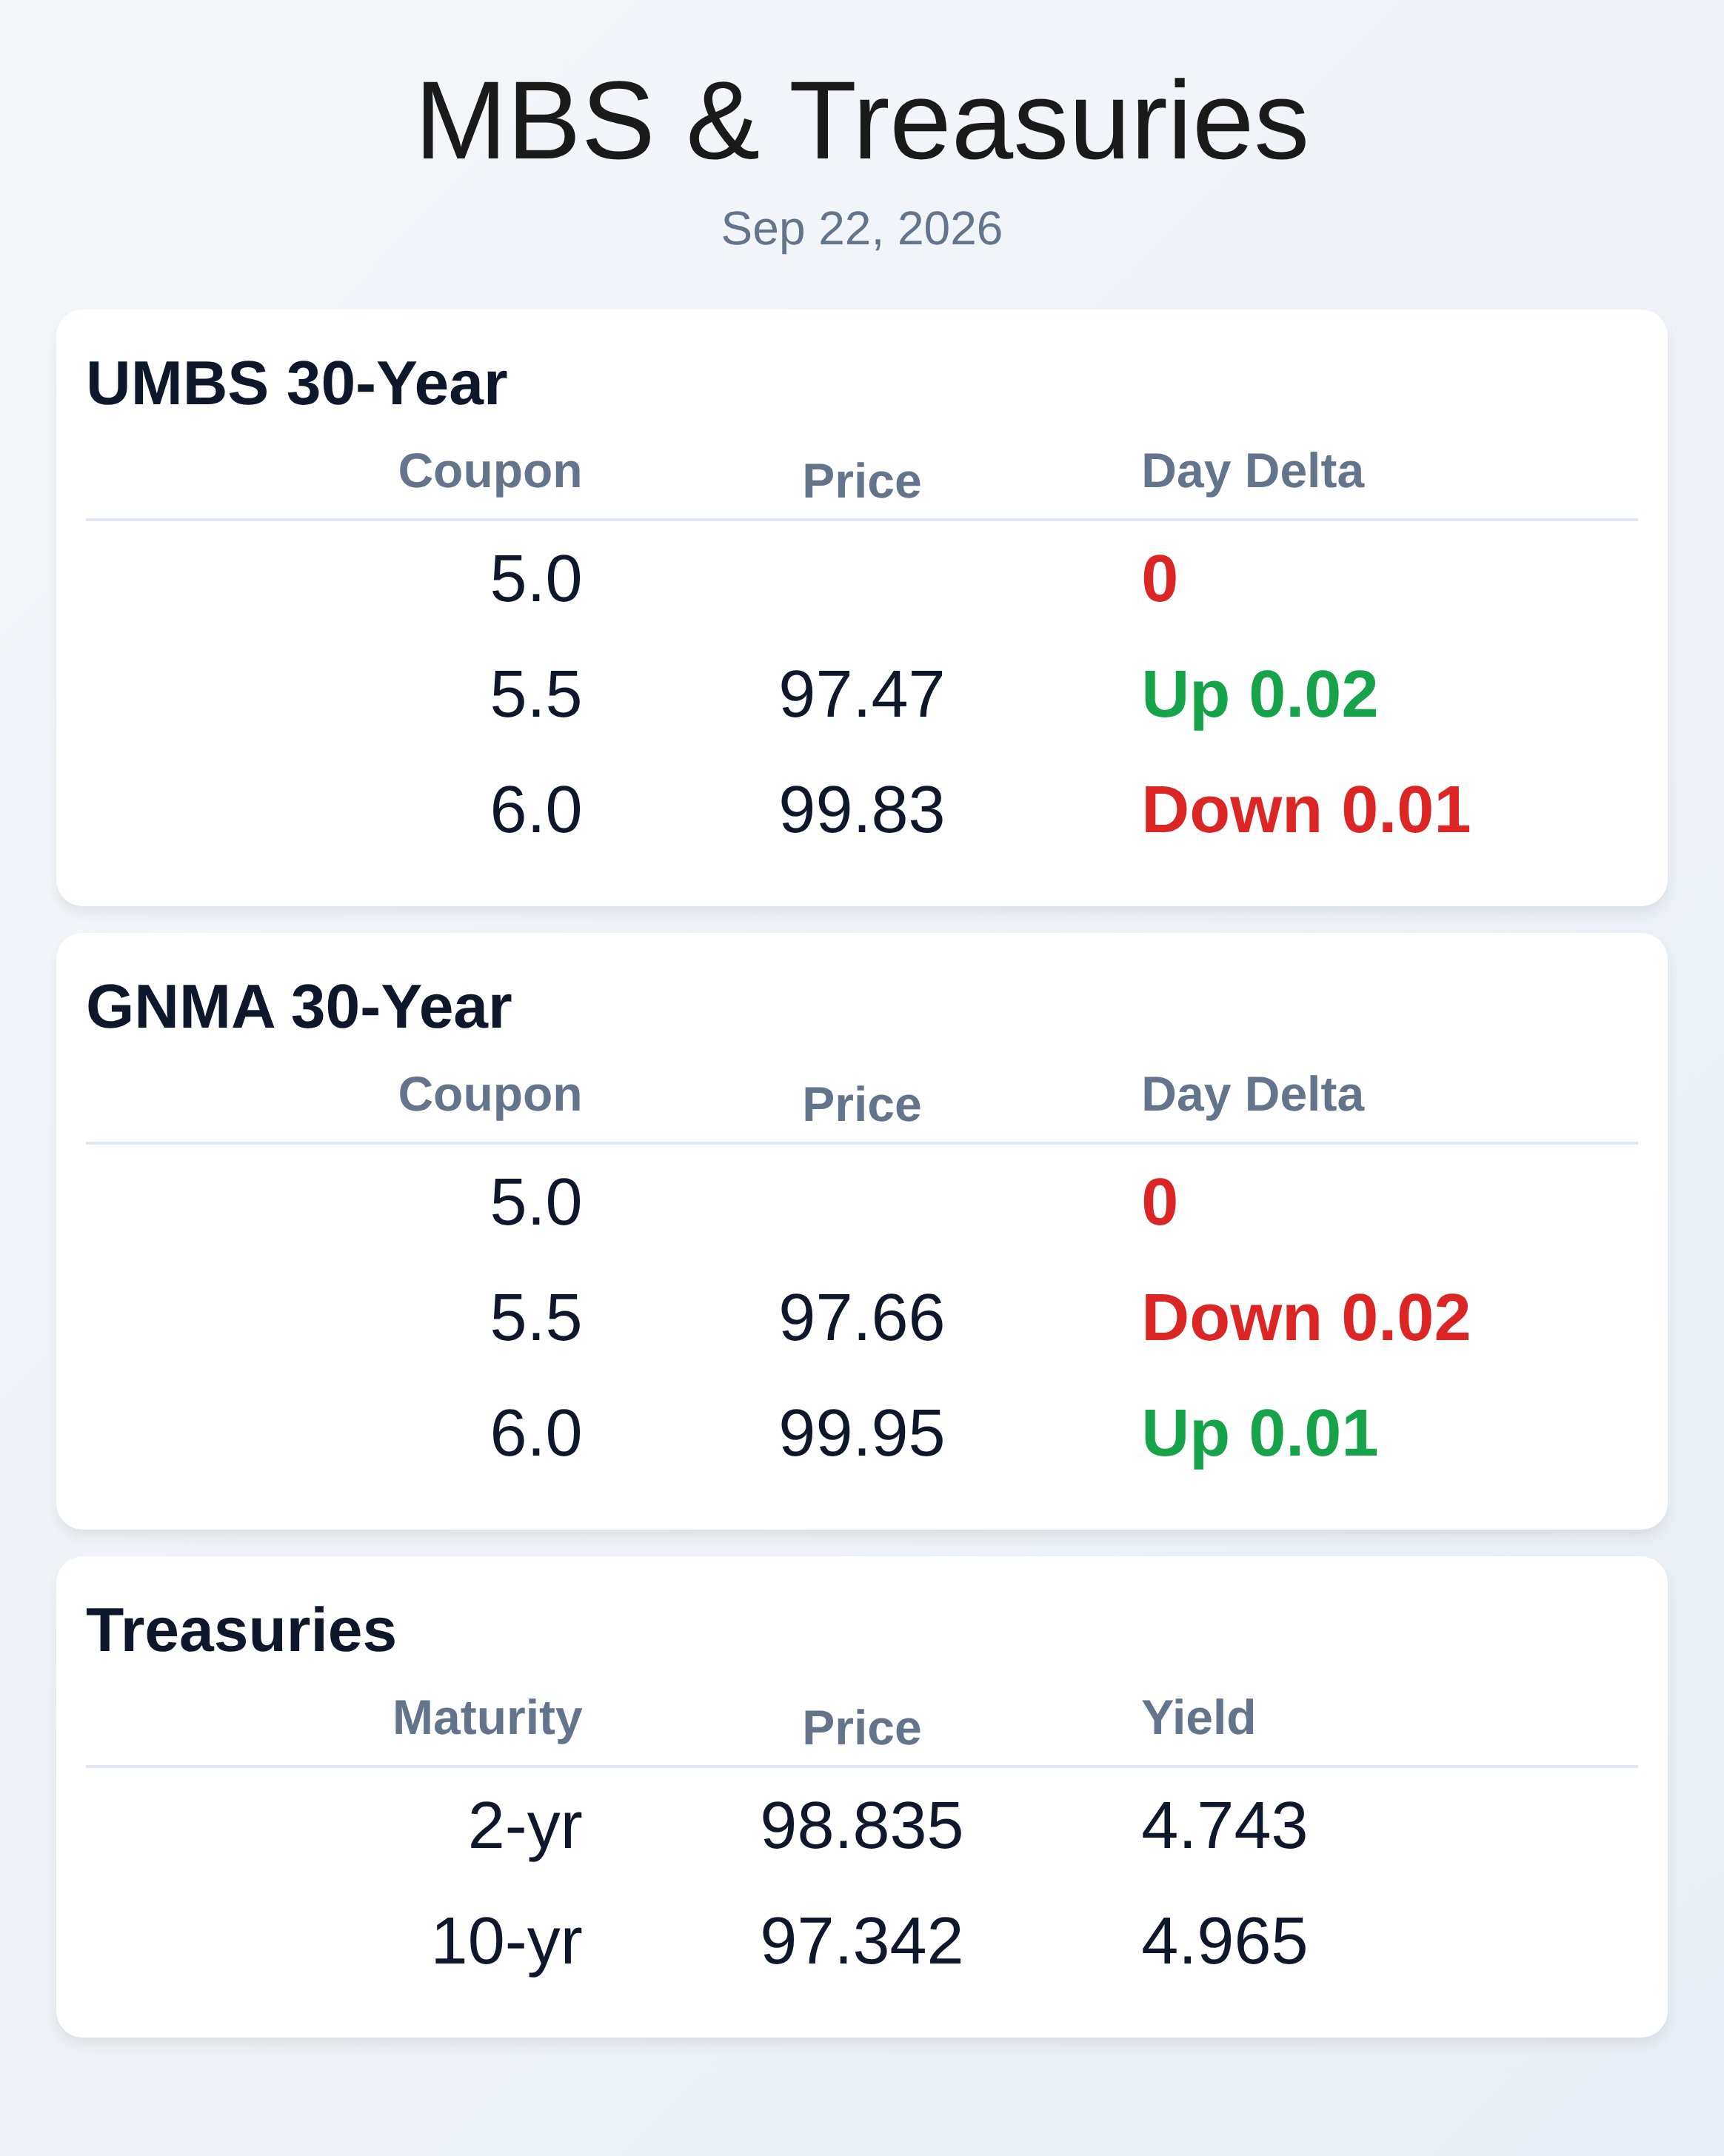
READ MORE **WTMS Blog Today = What's up in Mortgage Today (PM) - 09/22/2026** Bonds rebounded strongly after a volatile midday selloff, as geopolitical headlines regarding U.S.-Iran discussions pushed oil prices lower and yields back into positive territory. The 10-year Treasury fell to 4.949% on the latest diplomatic reports, while UMBS 6.0 closed up 2 basis points at 99.86. MBS moved down an eighth of a point from morning highs earlier in the session, but late-day momentum reversed the weakness. Oil price gyrations and war-related newsflow dominated trading rather than any scheduled economic data. Markets remain firmly anchored to technical levels until a clear directional break emerges. UMBS pricing showed mixed results throughout the day, with the 5.5 coupon ending flat and the 6.5 coupon down 4 ticks despite late-day gains. GNMA 30-year securities tracked similarly, with the 6.0 coupon barely positive on the day. These sideways moves reflect the broader uncertainty in mortgage spread values as headline risk continues to eclipse fundamental drivers. The range-bound trading pattern persists because neither bond bulls nor bears have a compelling macro catalyst this week. Lenders must prepare for potential reprices if geopolitical tensions escalate further. The 10-year yield closed near 4.955%, down just 3 basis points on the day but touching lows near 4.949% in afternoon trading. Treasury pricing benefited from flight-to-quality flows and the oil price decline tied to diplomatic progress reports. The 2-year remained flat while the 30-year yield climbed 11 basis points, steepening the yield curve modestly. This modest steepness creates tactical opportunities for mortgage hedging strategies. Intraday swings of 20+ basis points in 10-year yields highlight how shallow conviction remains among institutional traders. Geopolitical dynamics rather than economic fundamentals are steering the bond market. Headlines about Strait of Hormuz reopening talks and Trump UN speech comments regarding Iran negotiations created the day's directional moves. Oil fell sharply on these reports, which traditionally helps long-duration fixed-income assets outperform. The light data calendar means no competing narratives challenge war-related sentiment through week-end. Mortgage pros should recognize that this environment rewards flexibility in lock-float decisions. **Locking vs Floating** Wait for a definitive directional break before committing to aggressive positioning. The market remains trapped between 4.93% and 5.01% on the 10-year, with no inherent bullish or bearish bias underlying current price action. Geopolitical headlines provide tactical swings but not fundamental direction, so conservative lock-float positioning remains prudent. Oil price volatility and diplomatic developments will likely dominate through the UN General Assembly session. Only a clear technical break outside the established range should trigger a shift away from your neutral stance. **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | | 5.5 | 97.47 | 0.02 | | 6.0 | 99.83 | -0.01 | | 5.5 | 97.66 | -0.02 | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | | 2 yr | 4.743 | 98.835 | -0.007 | | 10 yr | 4.965 | 97.342 | 0.014 | | 30 yr | 5.301 | 97.377 | 0.02 | Market Data
LATEST ARTICLES

RECENT ARTICLES

Leaving Messages that Work

April 8th, 2021|Sell More|

Today's Blog post comes from  "Cold Calling Techniques (That Really Work)" by Stephan Schiffman Get it off Amazon Here Chapter 8: Leaving Messages that Work A lot of people just use [...]

The only thing better than a cold call

April 6th, 2021|Sell More|

Today's Blog post comes from  "Cold Calling Techniques (That Really Work)" by Stephan Schiffman Get it off Amazon Here  Referral Call Scripts.   The only thing better than a cold call.   Learn [...]

Article Archive
Subscribe

Send me some brain food

Go to Top