Loading...
HOME2023-01-22T13:43:33-07:00

Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.

I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.

I still remember how it started for me. It started in June of 2008. After 11  years …..Click to continue

Mortgage Today (AM) - 09/22/26 {{catlist}}
September 22, 2026
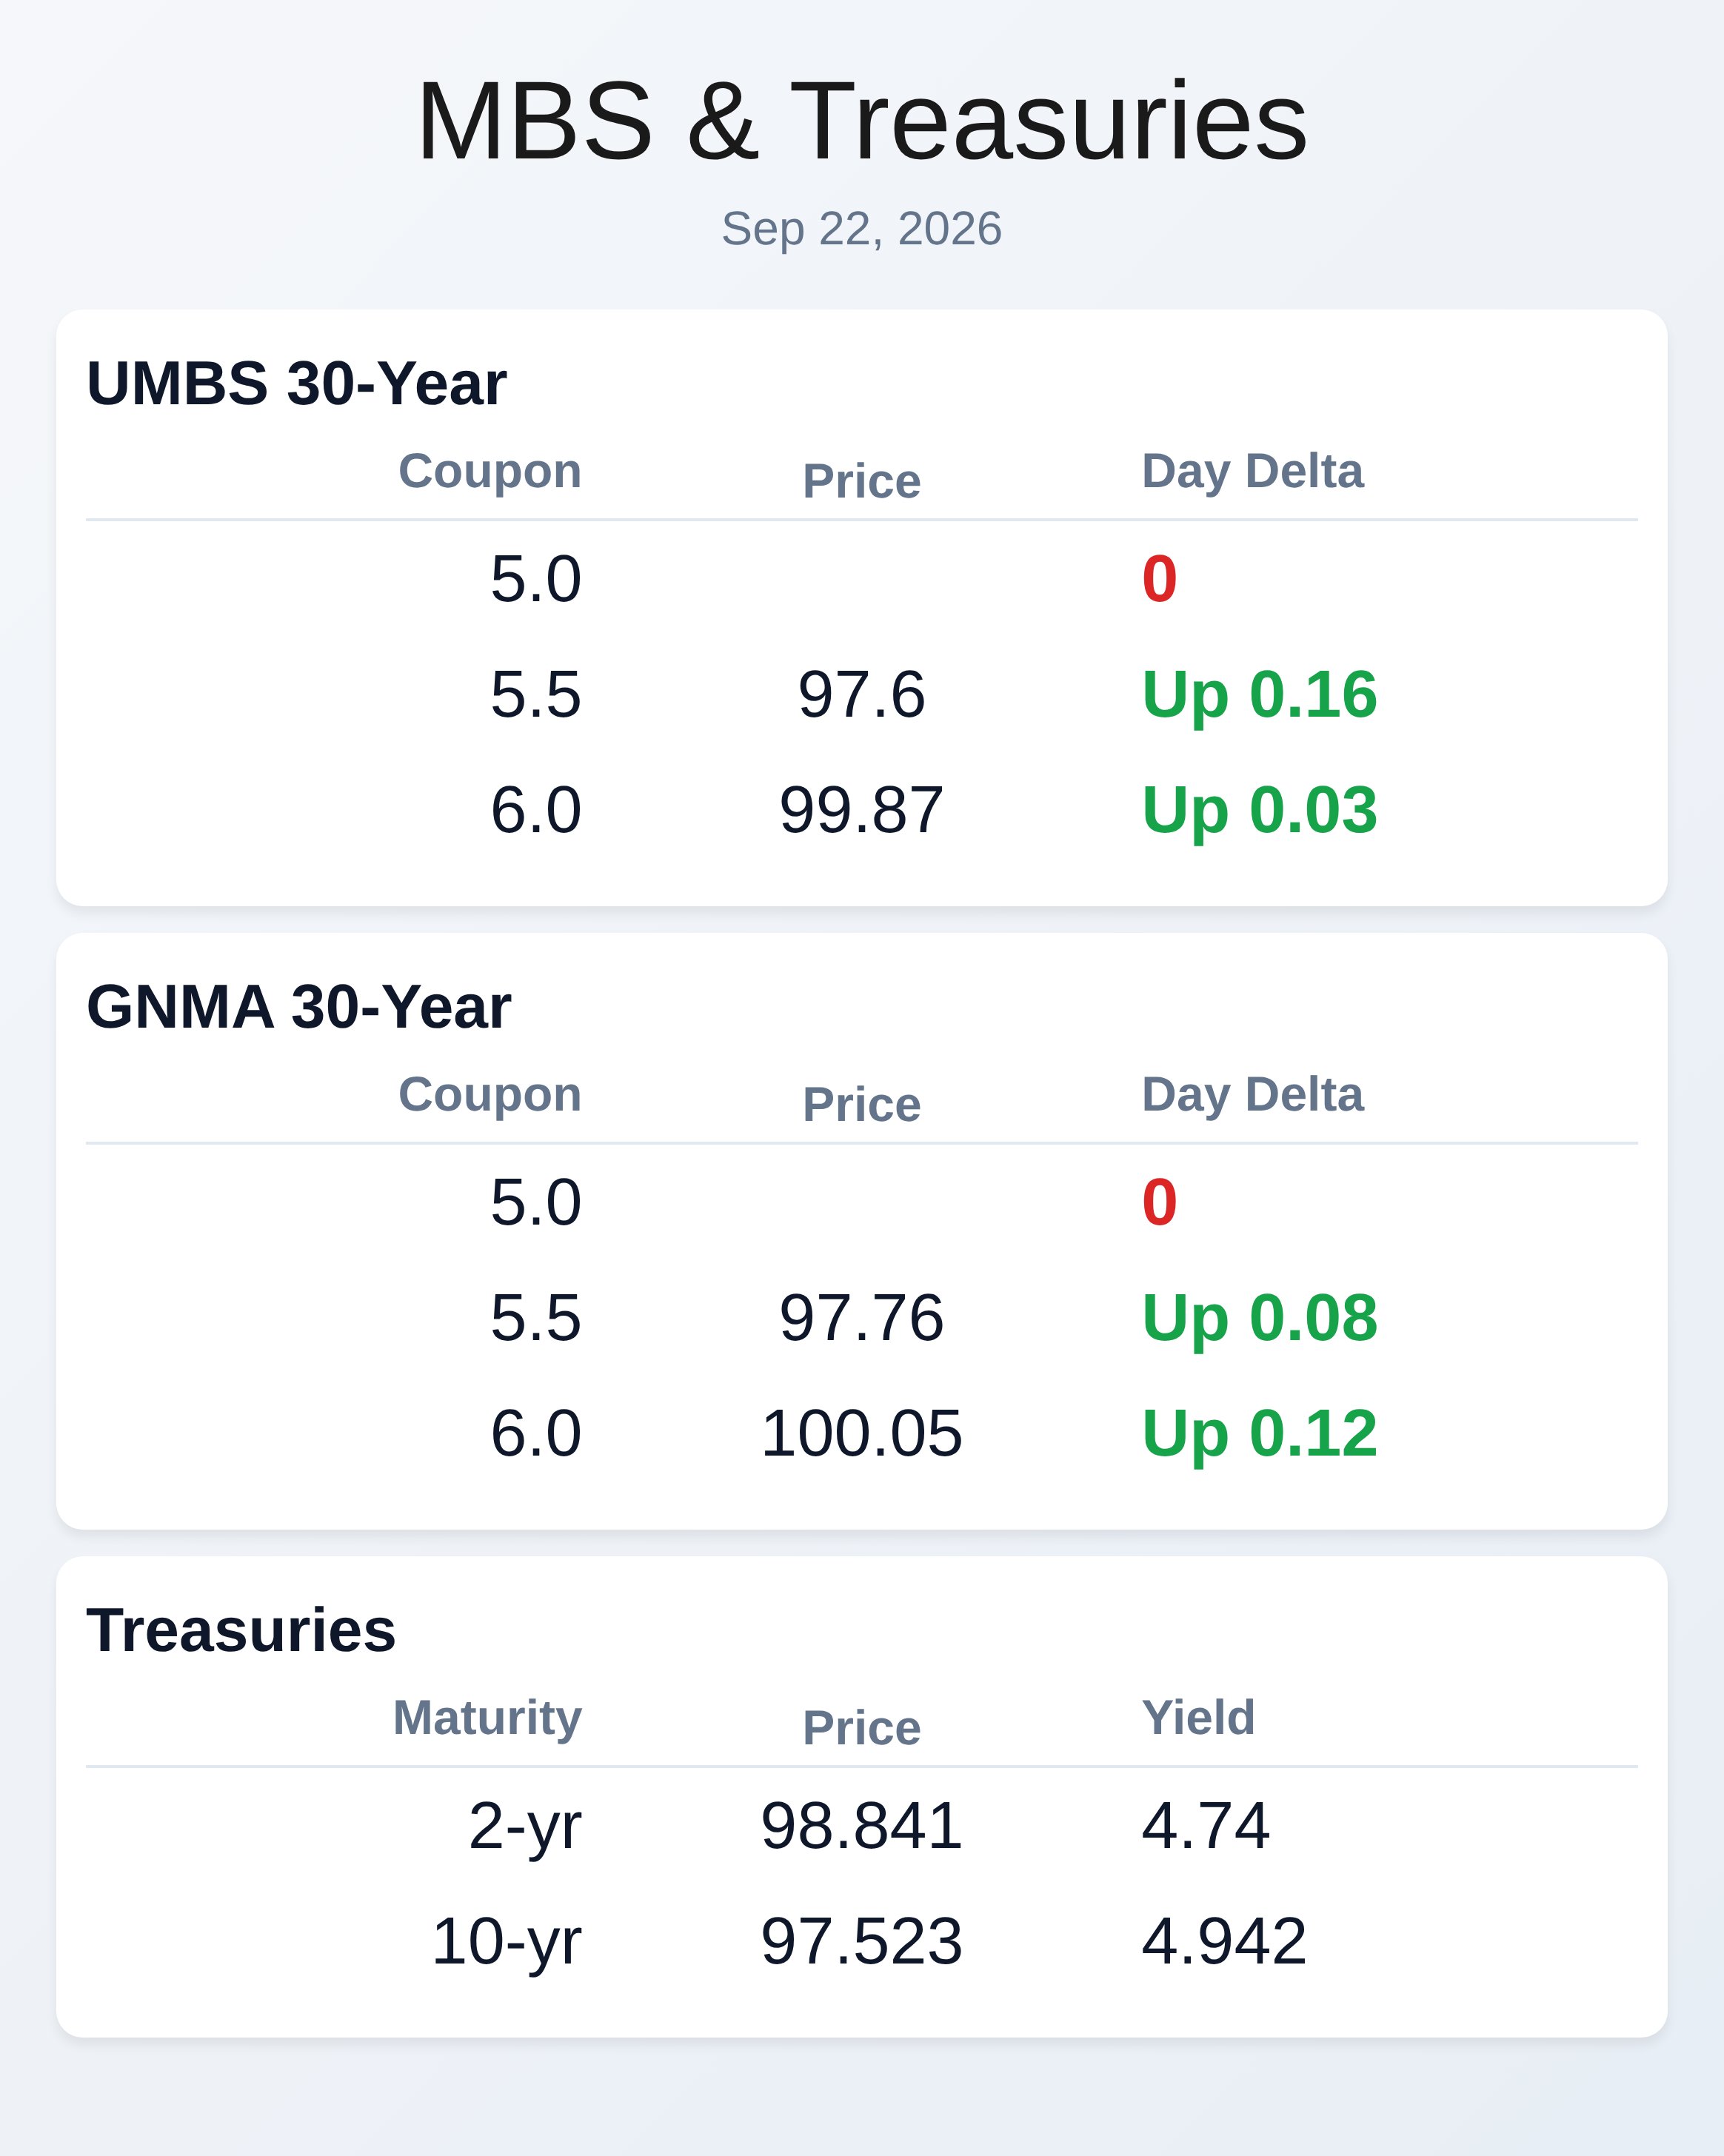
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/22/2026** Geopolitical headlines are moving bonds even when unconfirmed, as overnight markets rallied hard on reports—later denied by Iranian officials—that Tehran could reopen the Strait of Hormuz within seven days. Oil prices dropped instantly on the news, and Treasury yields followed lower across the curve. The market's logic is sound: financial traders believe some Iranian official probably did say something to multiple news agencies that disagreed with the government's official denials. What matters most to mortgage professionals is that bond prices improved for the second consecutive day, benefiting both MBS coupons and rate-lock opportunities. UMBS 6.0 securities closed yesterday at 99.90 and have moved higher in overnight trading, while the broader 6.5 coupon remains around 102.12 despite sideways momentum. GNMA 6.0 securities gained ground overnight, now trading at 100.08 with intraday gains of 0.15 points. Both agency MBS cohorts show modest strength in a risk-on environment driven by lower oil and geopolitical relief rather than fundamental economic improvements. Originators holding longer MBS positions may see modest cushion in their pipeline hedges, though the rally remains fragile without confirmed economic catalyst. The 10-year Treasury yield has declined 2.6 basis points from yesterday's close, now trading near 4.93 percent as markets digest overnight strength. Shorter maturities performed better, with the 2-year yield down 4 basis points to near 4.73 percent, while the 30-year fell 1.2 basis points to 5.27 percent. The two-to-ten spread narrowed to approximately 21 basis points yesterday, reflecting curve flattening amid Fed hawkish rhetoric. Today's $69 billion two-year note auction will test institutional demand in a market still bracing for potential October rate increases. Manufacturing cost claims across the mortgage industry range wildly from $125 to $12,500 per loan, creating confusion when lenders use these figures to recruit loan officers and compete for borrowers. The MBA reported Q2 2026 production expenses of $10,936 per loan for independent mortgage banks and $11,754 for retail-only lenders, establishing a standard that industry practitioners should reference when evaluating employer efficiency claims. Most cost variance stems from inconsistent definitions of what constitutes "manufacturing"—whether sales compensation, technology, fulfillment, or overhead are included—making peer comparisons nearly impossible. Loan officers deserve the same standardized clarity that consumers receive through the Loan Estimate when evaluating job opportunities and compensation promises. Without agreed-upon definitions, lenders risk making decisions based on incomplete or misleading data. Multiple Fed officials are scheduled to speak today, including Presidents Williams, Jefferson, and Barkin, though markets will remain cautious pending confirmation that underlying inflation is actually moving toward the 2.0 percent target rapidly. The Federal Reserve's recent hawkish pivot has restored some market confidence in its inflation-fighting independence, but the bar for tighter policy remains low and financial conditions are not yet restrictive enough to signal a policy shift. An October interest rate hike remains likely unless incoming economic data demonstrates sharp disinflation, putting pressure on mortgage originators to remain defensive on rate locks until clearer evidence emerges. Fed Chair Warsh's emphasis on controlling money and credit growth may eventually conflict with the central bank's continued balance sheet expansion, creating tactical opportunities for investors who fade near-term fed funds rallies. Builders continue using capital to temporarily buy down rates or permanently offer 30-year fixed mortgages at 1 percent below prevailing market rates rather than cut prices and devalue existing subdivisions. This builder-driven rate subsidy strategy reflects housing affordability pressure but masks the underlying demand weakness as residential volume continues declining across the industry. Credit unions are aggressively pursuing market share in this environment, leveraging their position in consumer financial relationships and willingness to undercut traditional originators on pricing. Mortgage professionals should expect continued competitive pressure on loan-level pricing and widening gain-on-sale margins as builders and credit unions fight for shrinking production volume. Today's bond market strength provides brief relief, but the structural headwind of declining volume remains the dominant issue facing originators. **Locking vs Floating** Technical resistance levels remain critical guides for mortgage professionals evaluating lock-versus-float decisions without guaranteed predictive power. The 4.94 percent level on 10-year yields represents important intermediate resistance, while 5.00 percent marks the ceiling many technical traders monitor closely. Friday's trading tested 5.00 percent repeatedly, but today's session approached 4.94 percent from below, suggesting potential momentum shifting. The conservative stance held since early July remains appropriate—lock aggressively until a definitive shift below 4.94 percent confirms sustained bond market rally momentum, as intraday MBS price movements alone provide insufficient confirmation of broader trend change. **Today's Events** 10:05 AM ET – Fed President Williams Speech 10:20 AM ET – Fed President Jefferson Speech 1:00 PM ET – Two-Year Note Auction ($69 billion) 1:00 PM ET – Fed President Barkin Speech **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | Market Data
Mortgage Today (PM) - 09/21/26 {{catlist}}
September 21, 2026
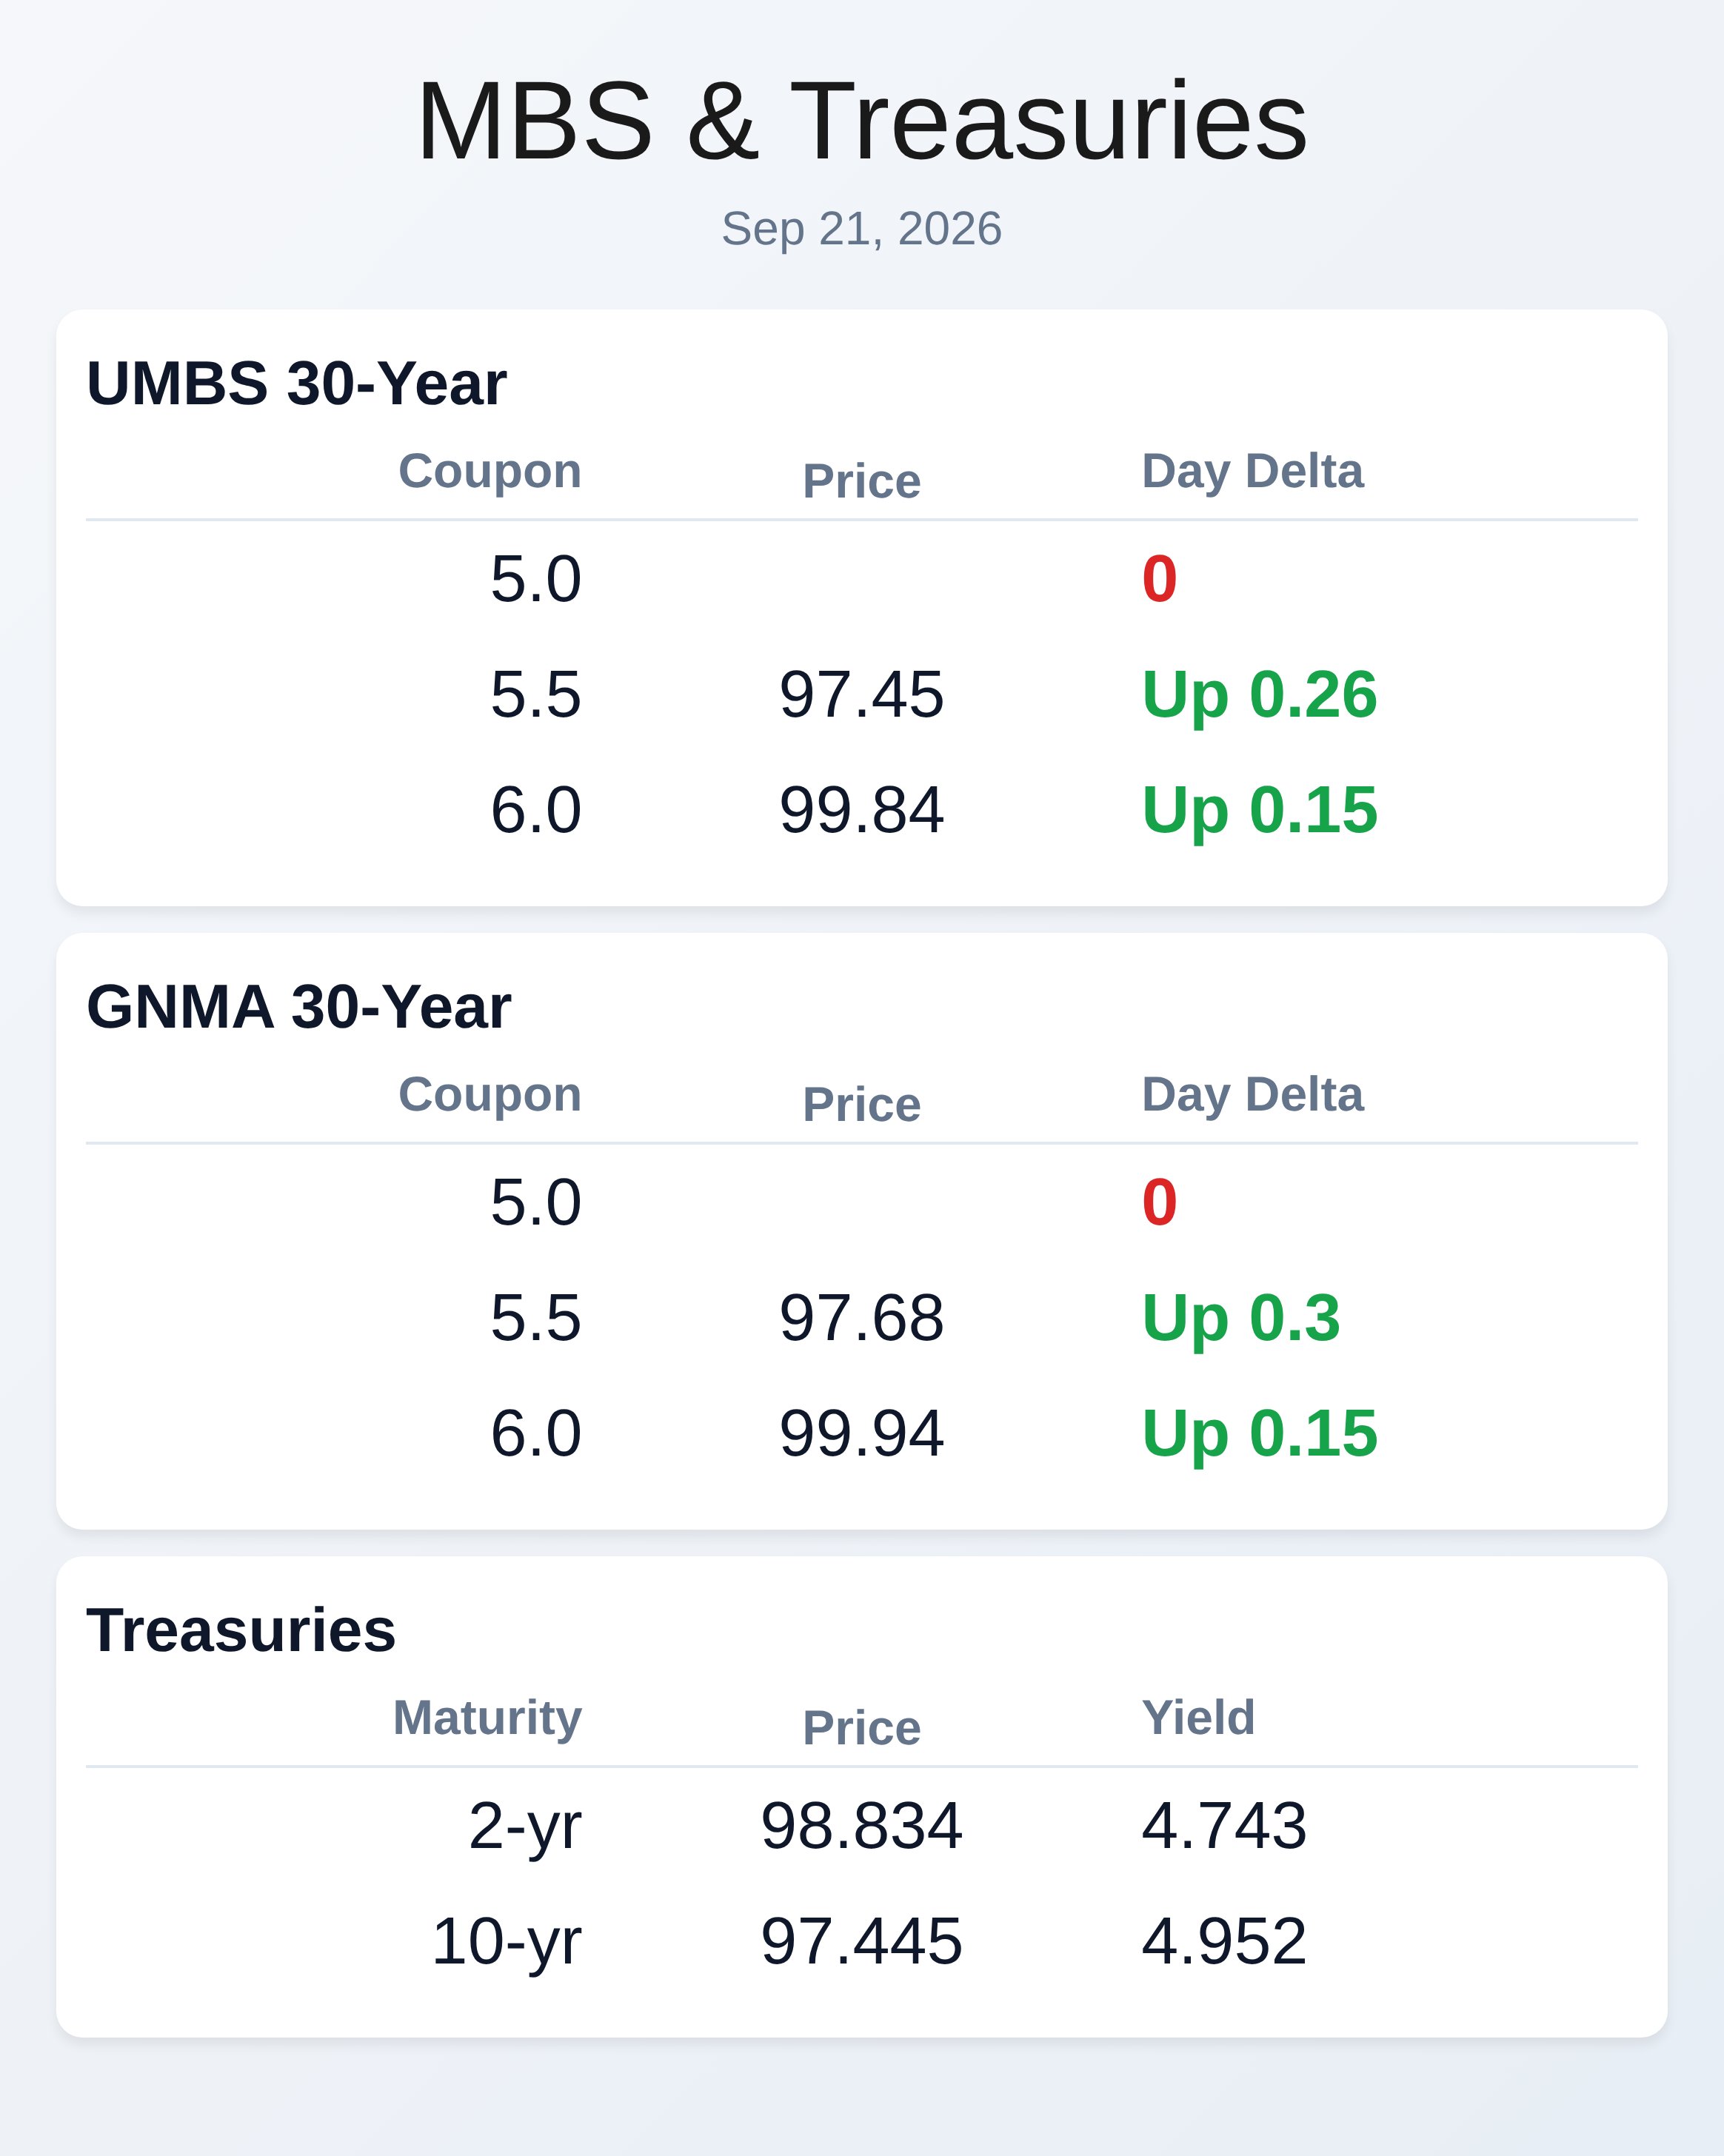
READ MORE **WTMS Blog Today = What's up in Mortgage Today (PM) - 09/21/2026** Bond markets finished sideways with a slight bid after an uneventful trading day in narrow ranges. The 10-year Treasury retreated 4.8 basis points to close near 4.95%, testing but failing to break the critical 4.94% technical level that would signal a meaningful rally ahead. UMBS 6.0 coupons gained 13 basis points to 99.82, while GNMA 6.0 coupons moved up 13 basis points to 99.91, suggesting modest security appetite despite persistent uncertainty about the Fed's remaining rate path. Mortgage origination forecasts are being cut sharply across the industry as rates have climbed and volumes decline. The Mortgage Bankers Association trimmed its 2027 forecast to $2.101 trillion from $2.144 trillion, with most analysts now expecting rates to settle near 6.7% through year-end. PennyMac's preliminary third-quarter data shows only $16.6 billion funded in July and August combined, pointing to roughly a 28% drop from second-quarter's monthly pace. Argus Research estimates volumes could fall at least 5% in the third quarter compared to the second quarter if rate levels persist. Better's internal corporate meltdown is shaping up as one of the year's most dramatic founder-versus-board conflicts. Vishal Garg and investor Daniel Lewis exchanged thousands of messages over roughly a year, bonding over corporate finance and distressed debt trading before Lewis joined the board in late July and orchestrated Garg's ouster within eight days. Garg is now attempting to remove Lewis and four other directors while Better has sued Garg for waging a "scorched-earth campaign," with both sides weaponizing private communications that paint a troubling picture of management philosophy at the troubled lender. Mutual of Omaha is exploring a strategic sale of its mortgage division after hiring Houlihan Lokey to assess options. The division operates 954 loan officers, produced $11.2 billion in volume over the past 12 months, and maintains 158 branches nationwide, making it one of the larger mortgage M&A opportunities this year. The reverse mortgage footprint alone is significant—Mutual of Omaha held the second-largest HECM position in 2026 with 3,343 endorsements through August, trailing only Finance of America, after leading the market in 2025 with 5,740 endorsements. A hidden opportunity exists in the September 27 through October 3 window when Realtor.com data shows buyers encounter more listings, less competition, and asking prices roughly $14,000 below summer peaks. However, last week's 19-basis-point rate increase adds approximately $42 to monthly payments on an average $332,800 loan, consuming more than half of the price benefit and pressuring buyers with older preapprovals. Loan officers should proactively contact borrowers who stepped away to refresh numbers and explore whether seller concessions or temporary buydown structures could make deals viable. AmeriTrust Mortgage is pursuing a $14.1 million lawsuit against investors, brokers, appraisers, and title companies over an alleged Baltimore-area DSCR fraud scheme involving roughly 90 investment-property loans. The complaint alleges properties purchased for $40,000 to $50,000 were quickly resold to affiliated entities for approximately $200,000, with financing based on inflated values that triggered immediate defaults and repurchase demands. This case underscores escalating industry warnings about DSCR loans featuring weak property valuations, questionable rental income, and inadequate counterparty verification that warehouse lenders and Wall Street have grown increasingly nervous about. **Locking vs Floating** Technical support and resistance levels remain crucial for lock-float decisions. The 4.94% level in 10-year yields represents important resistance; breaking below it could signal an early rally confirmation. The 5.00% ceiling must remain intact to avoid further upward pressure. Until yields definitively shift below 4.94%, the market stance favors conservative positioning in both lock and float recommendations rather than aggressive betting on substantial rate declines. **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | **GNMA 30yr** | Coupon | Price | Intra-Day Change | |---:|---:|---:| | 5.5 | 97.68 | 0.3 | | 6.0 | 99.94 | 0.15 | | 6.5 | 101.67 | 0.07 | **US Treasuries** | Term | Yield | Price | Intra-Day Yield Change | |---|---:|---:|---:| | 2 yr | 4.743 | 98.834 | -0.012 | | 3 yr | 4.813 | 98.791 | -0.025 | | 5 yr | 4.827 | 98.013 | -0.035 | | 7 yr | 4.882 | 97.76 | -0.047 | | 10 yr | 4.952 | 97.445 | -0.048 | | 30 yr | 5.284 | 97.619 | -0.043 | Subscribe free to WTMS Blog at WellThatMakesSense.com to receive daily market insights for mortgage originators. Market Data
Mortgage Today (AM) - 09/21/26 {{catlist}}
September 21, 2026
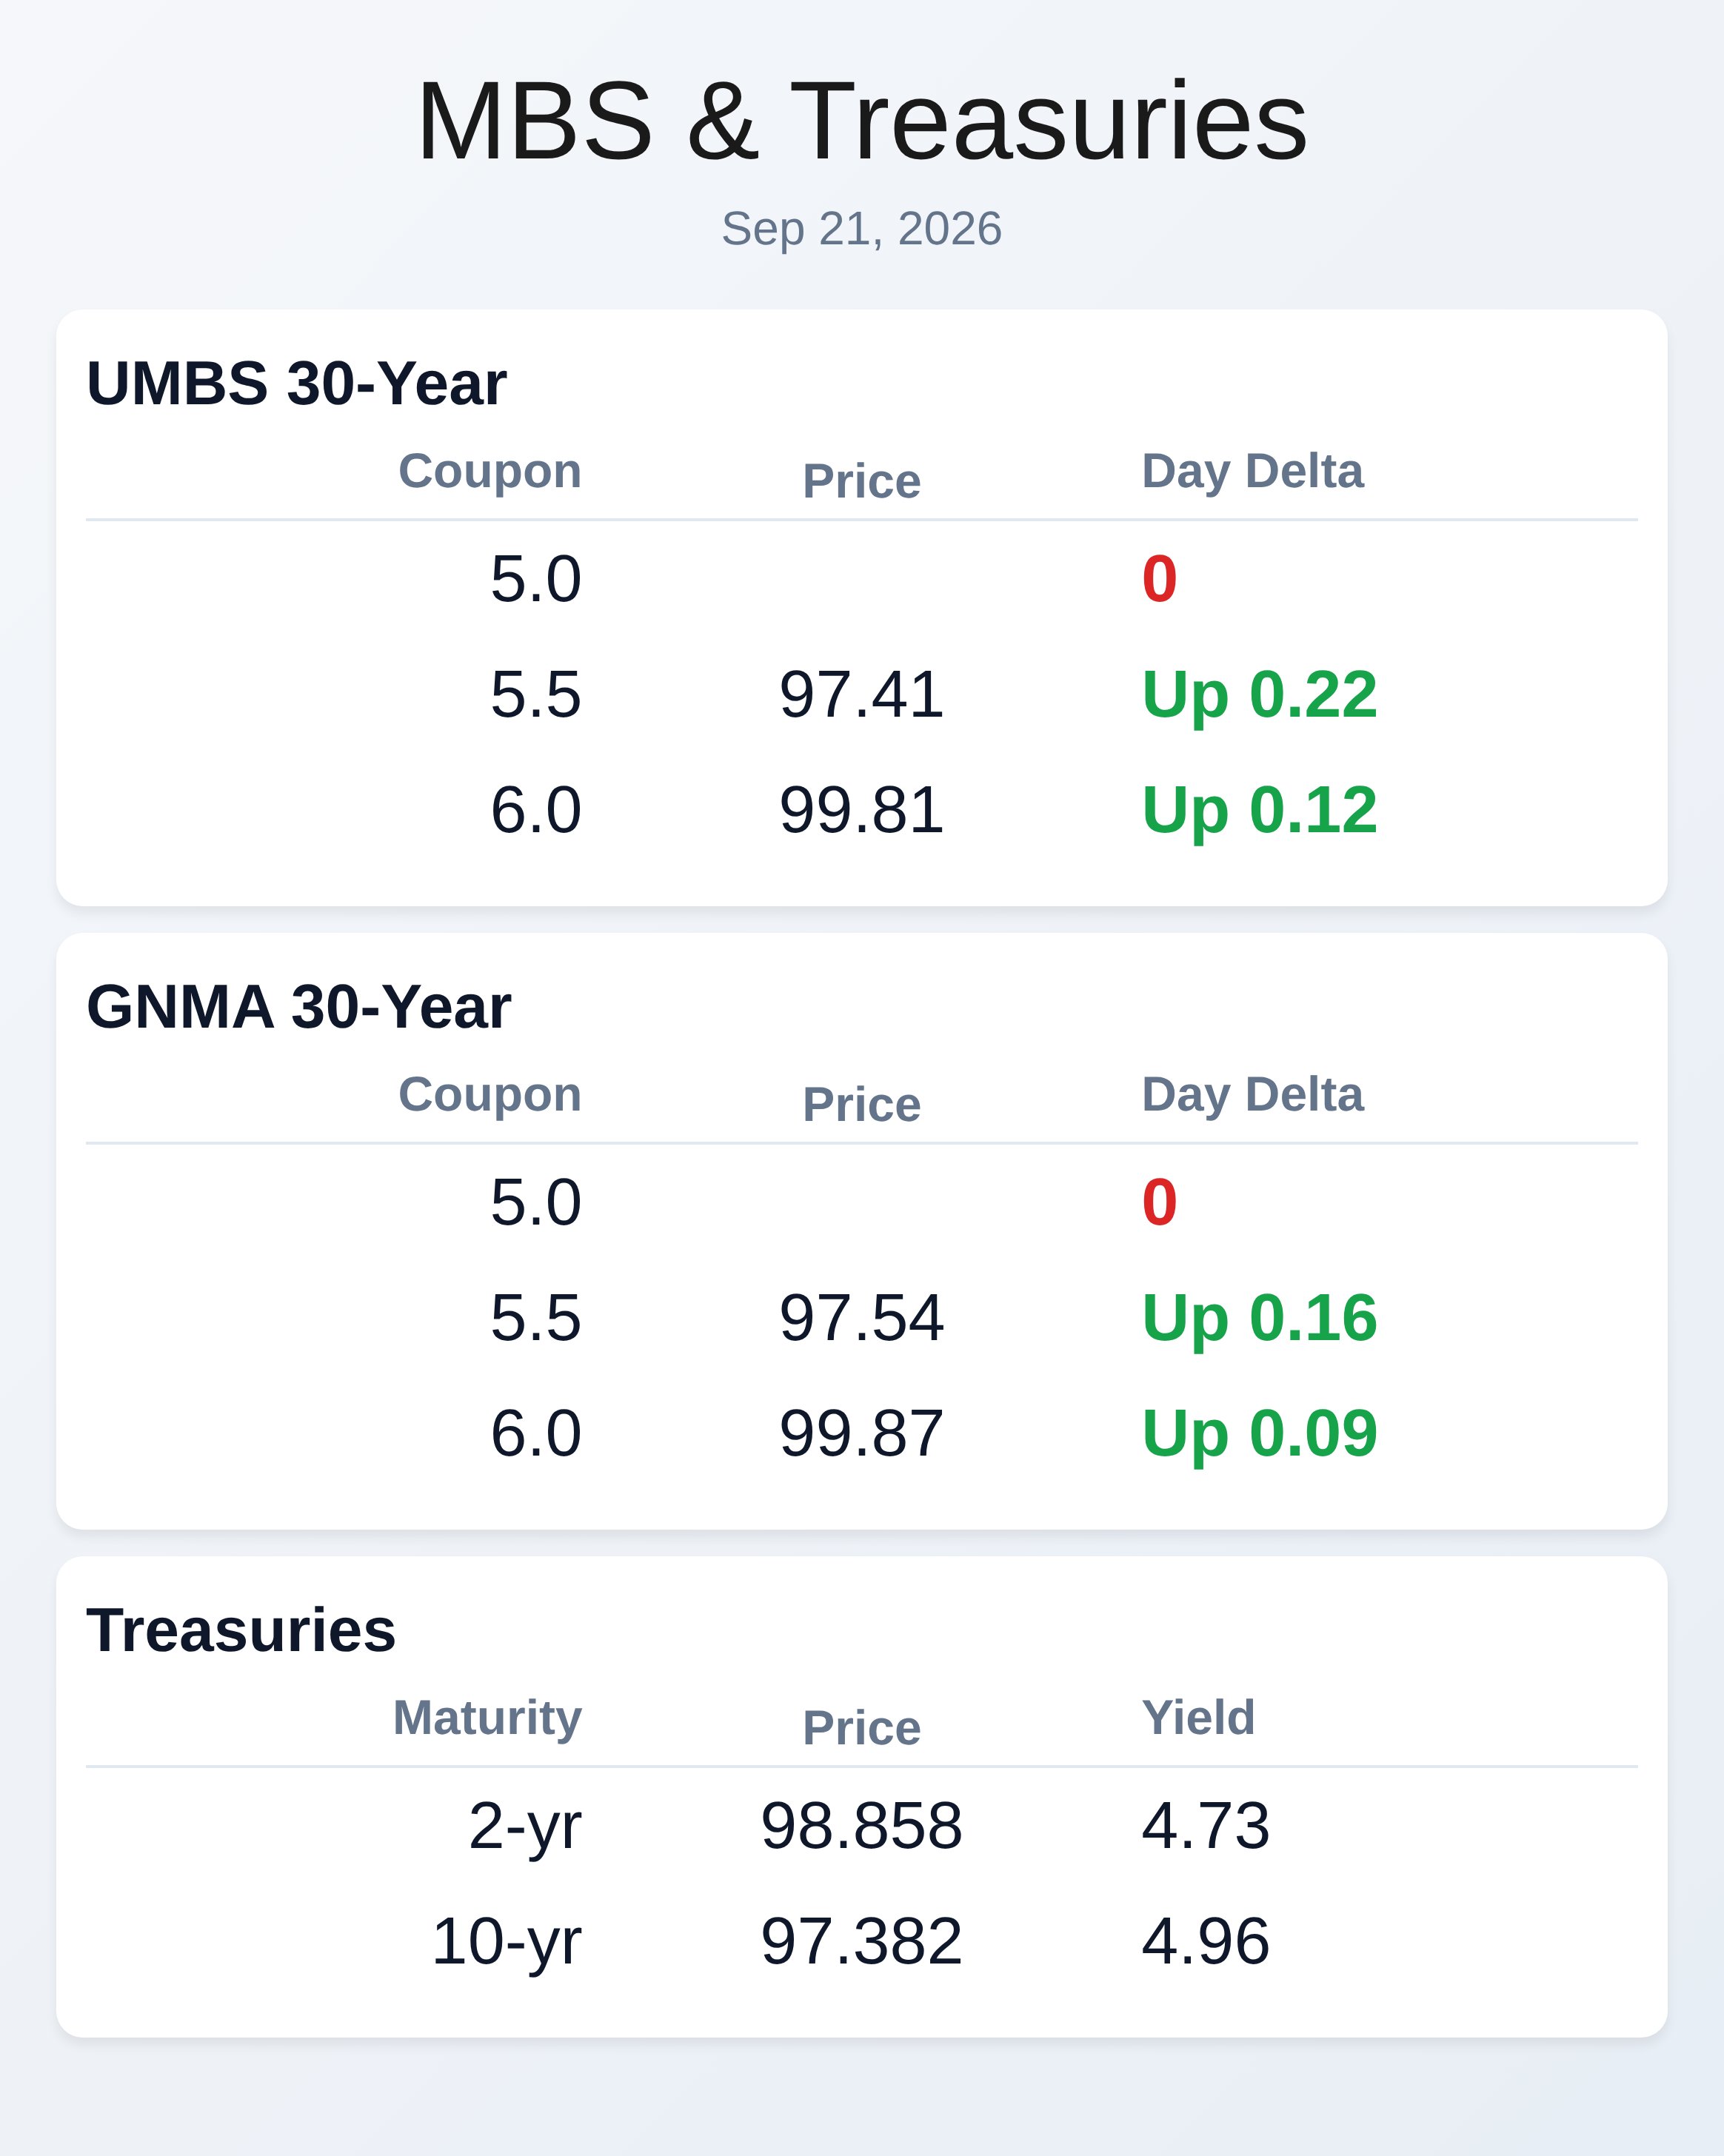
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/21/2026** The Federal Reserve's hawkish quarter-point rate hike to 3.75–4.00% last week sent shockwaves through Treasury markets, pushing the 10-year yield to nearly 5% multiple times as inflation fears resurface. The benchmark 10-year closed Friday at 5.00% and opened today at 4.95%, with traders caught between two competing forces: renewed confidence in Fed credibility versus persistent fiscal concerns demanding higher real yields. Agency MBS prices responded positively in pre-market trading, up 0.125–0.250 from Friday's close, though mortgage spreads remain tactically cheap on a spread basis. Buyers remain hesitant to add risk until Treasury yields establish a stable trading range. The choppy environment also complicated mortgage hedging, with the deeply special FNCL 6.5 roll straining extension and financing costs for pipeline hedgers. Economic data this morning delivered mixed signals for mortgage market momentum. Jobless claims came in better than expected at 196K versus 208K forecast, while continued claims fell to 1.730M from 1.774M previously. However, housing starts declined to 1.275M in August versus 1.31M expected, and building permits fell short at 1.394M versus 1.41M forecast. The Philly Fed Business Index surprised to the upside at 37.8 versus 30.5 expected, but Philly Fed Prices Paid accelerated to 48.60, signaling persistent pricing pressure in manufacturing. These data points reinforce that growth remains resilient even as inflation concerns persist, keeping the Fed's rate-hiking bias intact. UMBS 30-year coupon prices showed modest intra-day gains this morning across the curve. The 5.5 coupon gained 0.22 points to 97.41, the 6.0 coupon rose 0.12 to 99.81, and the 6.5 coupon added 0.11 to 102.05. GNMA 30-year coupons performed similarly, with the 5.5 coupon at 97.54 (up 0.16), the 6.0 at 99.87 (up 0.09), and the 6.5 at 101.76 (up 0.16). The modest gains suggest buyers are testing the market after Friday's heavy selling, but conviction remains limited until yield stability improves. These modest moves reflect the cautious tone across Agency MBS as traders await clearer Treasury direction. Multiple conforming loan limit increases effective immediately or this week signal lender confidence despite rate volatility. Pennymac raised its conforming limit to $850,000, the highest announced increase, ahead of FHFA's official 2027 announcement expected in December. UWM, Newrez, Loan Stream, and AmeriHome all announced increases, with limits ranging from $845,000 to $850,000 for mainland properties. These expansions allow lenders to compete more aggressively for higher-balance loans that would otherwise fall into non-Agency territory. The coordinated moves suggest lenders are preparing inventory strategies for a tighter conventional landscape. Industry consolidation is reshaping borrower relationships and recapture strategy as lenders compete on technology innovation and servicing capabilities. This week's ACUMA conference in Las Vegas attracts 800 registrants, with AI and automation as central themes across vendor booths and lender meetings. Spring EQ, mLoop, Balerion, and other platforms are emphasizing speed (top performers closing home equity loans in under 10 days) and seamless borrower experience through white-labeling and automated verification. The competitive pressure to reduce friction and improve processing speeds is accelerating technology adoption across the mortgage ecosystem. Pipeline hedging and mortgage volatility remain key headwinds as the market awaits clearer direction on inflation and Fed policy. The deeply special FNCL 6.5 roll created financing strain for hedgers last week, illustrating how extended duration and low prepayment sensitivity magnify costs in volatile markets. With 16 of 18 Fed officials now expecting at least one more rate hike this year, the risk of higher volatility persists until energy prices stabilize and September inflation data prove benign. For now, the default posture remains conservative on lock/float decisions until a definitive Treasury rally emerges to justify a shift in borrower positioning. **Locking vs Floating** Technical resistance at 4.94% and 5.00% in 10-year yields has created important inflection points for lock/float decisions. One-off distortions in the bond market today suggest waiting for next week to better assess post-Fed momentum. The consensus view remains conservative: maintain neutral positioning until a definitive shift or rally emerges that justifies moving away from cautious borrower guidance. **Today's Events** Building Permits (Aug): 1.394M vs 1.41M forecast, 1.433M prior Continued Claims (Sep/05): 1.730M vs 1.780K forecast, 1.774K prior Housing Starts (Aug): 1.275M vs 1.31M forecast, 1.239M prior Jobless Claims (Sep/12): 196K vs 208K forecast, 206K prior Philly Fed Business Index (Sep): 37.8 vs 30.5 forecast, 47.4 prior Philly Fed Prices Paid (Sep): 48.60 vs forecast unavailable, 40.90 prior **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | **UMBS 30-Year** | Coupon | Price | Intra-Day Change | |---|---|---| | 5.5 | 97.41 | 0.22 | | 6.0 | 99.81 | 0.12 | | 6.5 | 102.05 | 0.11 | **GNMA 30-Year** | Coupon | Price | Intra-Day Change | |---|---|---| | 5.5 | 97.54 | 0.16 | | 6.0 | 99.87 | 0.09 | | 6.5 | 101.76 | 0.16 | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | |---|---|---|---| | 2-Year | 4.73 | 98.858 | -0.025 | | 3-Year | 4.803 | 98.818 | -0.026 | | 5-Year | 4.823 | 98.031 | -0.032 | | 7-Year | 4.89 | 97.713 | -0.039 | | 10-Year | 4.96 | 97.382 | -0.04 | | 30-Year | 5.294 | 97.471 | -0.033 | Subscribe free to stay ahead of daily mortgage market moves at WellThatMakesSense.com Market Data
LATEST ARTICLES

RECENT ARTICLES

Article Archive

April 1st, 2019|0 Comments

A Polite Version of "Get your head out of your as…….." One of my largest literary frustrations is that someone wrote this great, great sales book under an assumed name.   So I can't [...]

March 30th, 2019|0 Comments

** For the Mortgage Peeps It doesn't help lender's relationships with their warehouse banks and correspondent investors when independent mortgage banks, and mortgage subsidiaries of chartered banks, reported a net loss of $200 for [...]

Most Influential Book on Influence Ever (Tip 4)

March 29th, 2019|0 Comments

This is part of a series of information/stories delivered from the INCREDIBLE book,  "Influence: The Psychology of Persuasion" by Robert Cialdini.     If you work or live a life where you have to get people [...]

Most Influential Book on Influence Ever (Tip 3)

March 27th, 2019|0 Comments

This is part of a series of information/stories delivered from the INCREDIBLE book,  "Influence: The Psychology of Persuasion" by Robert Cialdini.     If you work or live a life where you have to get people [...]

Do you have the GUTS to be GREAT!?

March 26th, 2019|0 Comments

Here’s a really poignant excerpt from “The Way Of The Superior Man” by David Deida...fits perfectly into 10x’ing our lives: LEAN JUST BEYOND YOUR EDGE In any given moment, a man’s growth is optimized [...]

Most Influential Book on Influence Ever (Tip 2)

March 25th, 2019|0 Comments

This is part of a series of information/stories delivered from the INCREDIBLE book,  "Influence: The Psychology of Persuasion" by Robert Cialdini.     If you work or live a life where you have to get people [...]

Most Influential Book on Influence Ever

March 22nd, 2019|0 Comments

The Science of Persuasion Do you work in sales or in a capacity that is improved when you can influence people?   Hint:  You all are.    Then you HAVE TO, HAVE TO, HAVE TO read [...]

Official First Post

March 20th, 2019|0 Comments

Yes, I'm aware there were other posts before this.  But I do hereby declare this as my First Official Blog Post! And, welp, yeah. This seems like a natural to use as my first [...]
Subscribe

Send me some brain food

Go to Top