Loading...
HOME2023-01-22T13:43:33-07:00

“Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.

I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.

I still remember how it started for me. It started in June of 2008. After 11  years …..Click to continue

Mortgage Today (AM) - 09/25/26 {{catlist}}
September 25, 2026
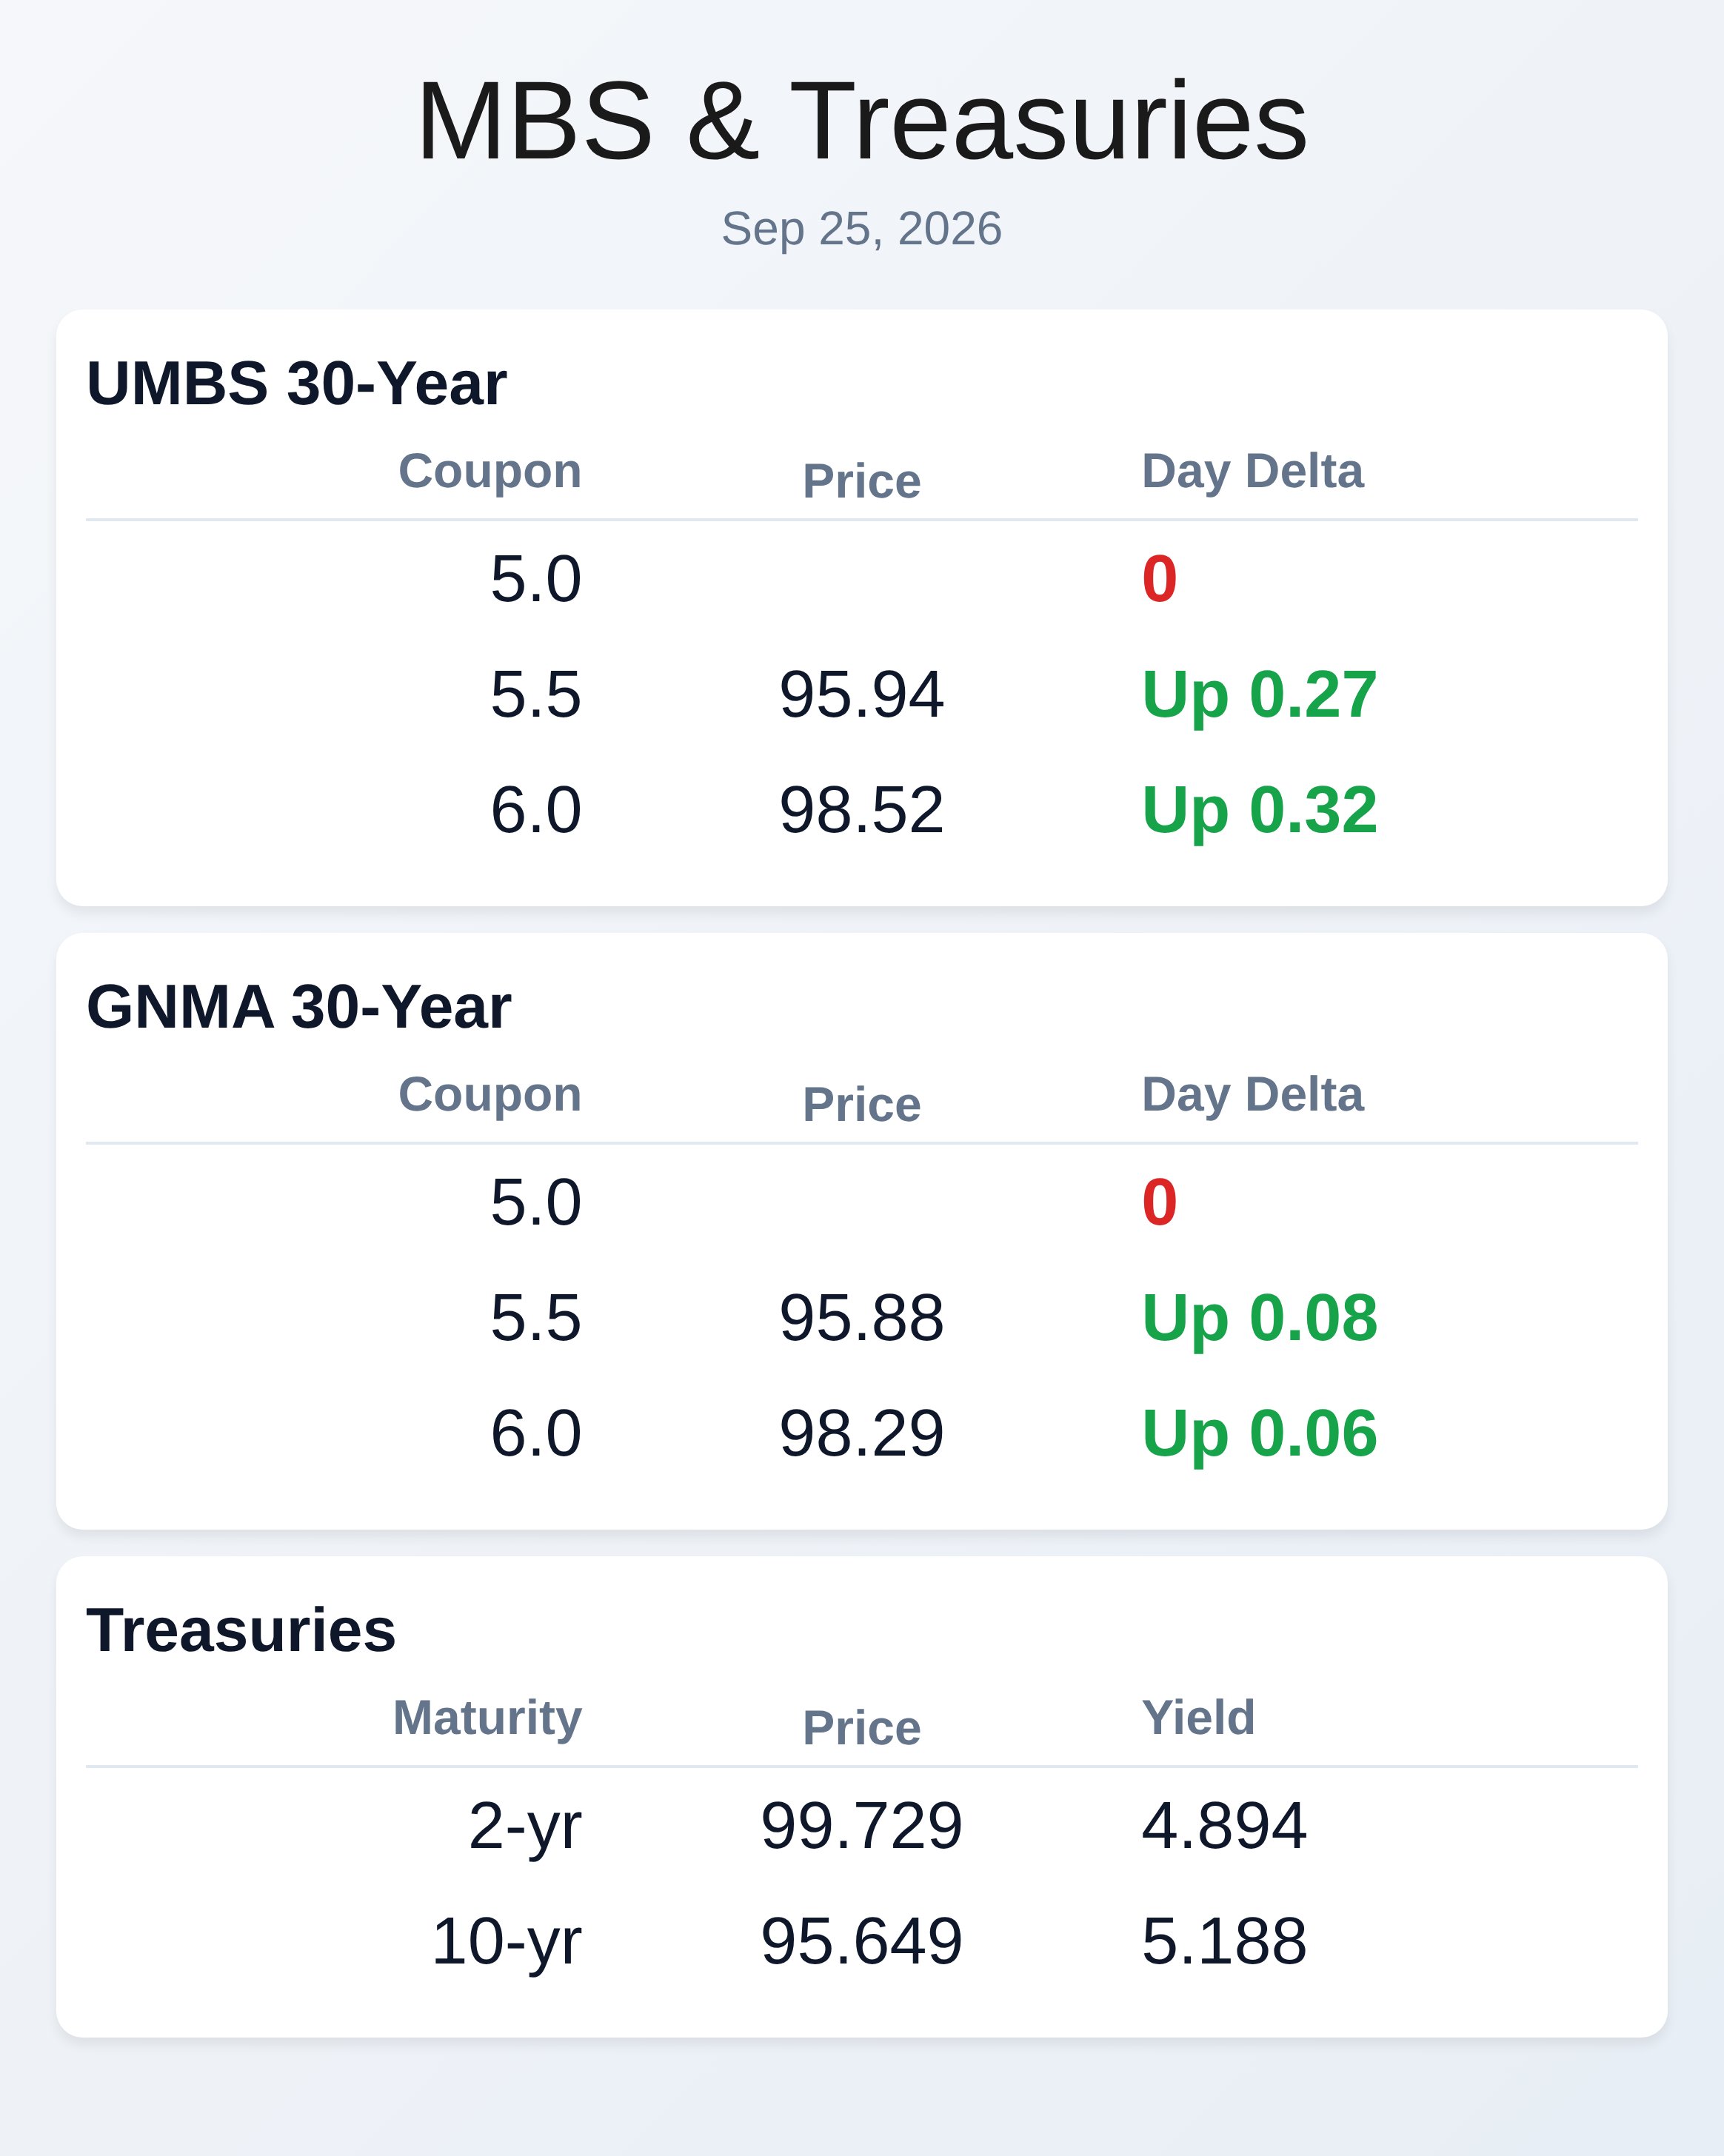
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/25/2026** Mortgage payment relief arrived in August as median monthly payments fell to $2,162, down from $2,175 in July, while household earnings climbed 4.1% year-over-year to outpace the 2.9% payment increase. The Mortgage Bankers Association's Purchase Applications Payment Index dropped to 154.3, marking a 0.6% decline that signals improving affordability even as 27 states reported payment declines. FHA borrowers benefited most with median payments falling to $1,856, though conventional borrowers saw their payments rise slightly to $2,188. This data arrives amid broader market pressures where Treasury yields have climbed nearly 44 basis points this month alone. Core capital expenditure data crushed expectations at 1.6% versus a 0.5% forecast, signaling persistent inflation pressures that keep the Federal Reserve in a challenging position as it balances growth signals against stubborn price persistence. Durable goods orders came in flat at 0% when economists predicted a decline of 0.4%, suggesting manufacturing resilience despite rising interest rate headwinds. The combination of stronger-than-expected inflation data and solid economic output is pushing the market to price in a prolonged higher-for-longer rate environment. Morgan Stanley economists now expect the Fed to stop hiking after December and March—about one hike short of market expectations—but inflation readings like today's suggest the path remains uncertain. The housing market is shifting leverage toward buyers as new home sales rebounded 6.4% to reach an 684,000 annualized rate in August, the highest level since December 2025, while median prices fell 5.8% year-over-year to $393,700. Inventory of new homes held steady at 483,000 units with an elevated 8.5-month supply, though just 112,000 homes are completed and ready for immediate occupancy. The Midwest led regional gains with an 84.9% monthly jump, while the Northeast and West posted sharp declines, signaling uneven demand across geographies. Existing home inventory climbed 46% from 2023 levels, forcing sellers to adjust pricing with nearly one in five homes receiving price cuts in August—the highest share for that month since 2020. HouseCanary received court approval to continue operations in Chapter 11 bankruptcy, allowing the data and appraisal services company to maintain customer support while it restructures and pursues a potentially $175 million claim against Rocket Close from a March 2026 jury award. The filing came after the company defaulted on a $30 million loan, but debtor-in-possession financing now provides liquidity for operations, employee obligations, and customer programs. The bankruptcy could ripple through the market given Google's reliance on HouseCanary technology for its national home-listings program launched in June. Rocket Companies disputes the jury award and plans to appeal, creating uncertainty around both companies' near-term strategic direction. PLACE's acquisition of Maxwell—a mortgage fintech serving over 400 financial institutions and supporting $130 billion in annual mortgage transactions—expands PLACE's origination capabilities by adding point-of-sale, business intelligence, fulfillment, and private-label solutions to its real estate platform. Maxwell touches nearly 10% of U.S. mortgage originations and operates independently under CEO John Paasonen with over 100 employees now joining PLACE. The deal follows PLACE's August purchase of Radian Group's real estate services business and a pending acquisition of Radian's title operations expected to close in the fourth quarter. This consolidation trend reflects the industry's ongoing push toward integrated platforms. The 10-year Treasury yield is currently trading at 5.171%, down 3.5 basis points from the previous close, while UMBS mortgage-backed securities are showing modest strength with the 6.0 coupon up 0.32 points to 98.52. Market participants are grappling with robust economic data, persistent inflation pressures, and an enormous supply of U.S. government debt that continues to pressure yields higher throughout the month. The persistent cheapening across the coupon stack and disappointing long-end Treasury auctions suggest demand may be testing its limits, with markets now asking who will be the buyer of size at these levels. Fixed-income traders have rapidly adjusted projections to price in a much higher-for-longer Fed path with the terminal rate approaching 4.86%, nearly 100 basis points above the Fed's own September projections. **Locking vs Floating** Mortgage originators face a challenging environment where catching falling knives before they land remains dangerous, despite the past 48 hours of selling pressure. Strong economic data and persistent inflation suggest Treasury yields may have further room to climb before bonds become attractive purely on return-to-value metrics. The key question isn't whether this is the bottom, but rather whether borrowers lock in current rates or continue floating in hopes of future relief that remains uncertain. **Today's Events** Core Capital Expenditure (August): 1.6% vs 0.5% forecast, 0.2% previous Durable Goods Orders (August): 0% vs -0.4% forecast, 1.1% previous Final September University of Michigan Consumer Sentiment (scheduled later today) Remarks from New York Fed President Williams and Kansas City Fed President Schmid **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | | 5.5 | 95.94 | 0.27 | | 6.0 | 98.52 | 0.32 | | 5.5 | 95.88 | 0.08 | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | | 2 yr | 4.894 | 99.729 | -0.031 | | 3 yr | 4.975 | 98.347 | -0.032 | | 5 yr | 5.033 | 99.855 | -0.021 | | 7 yr | 5.109 | 99.367 | -0.019 | | 10 yr | 5.188 | 95.649 | -0.013 | | 30 yr | 5.487 | 94.7 | 0.01 | Market Data
Mortgage Today (AM) - 09/24/26 {{catlist}}
September 24, 2026
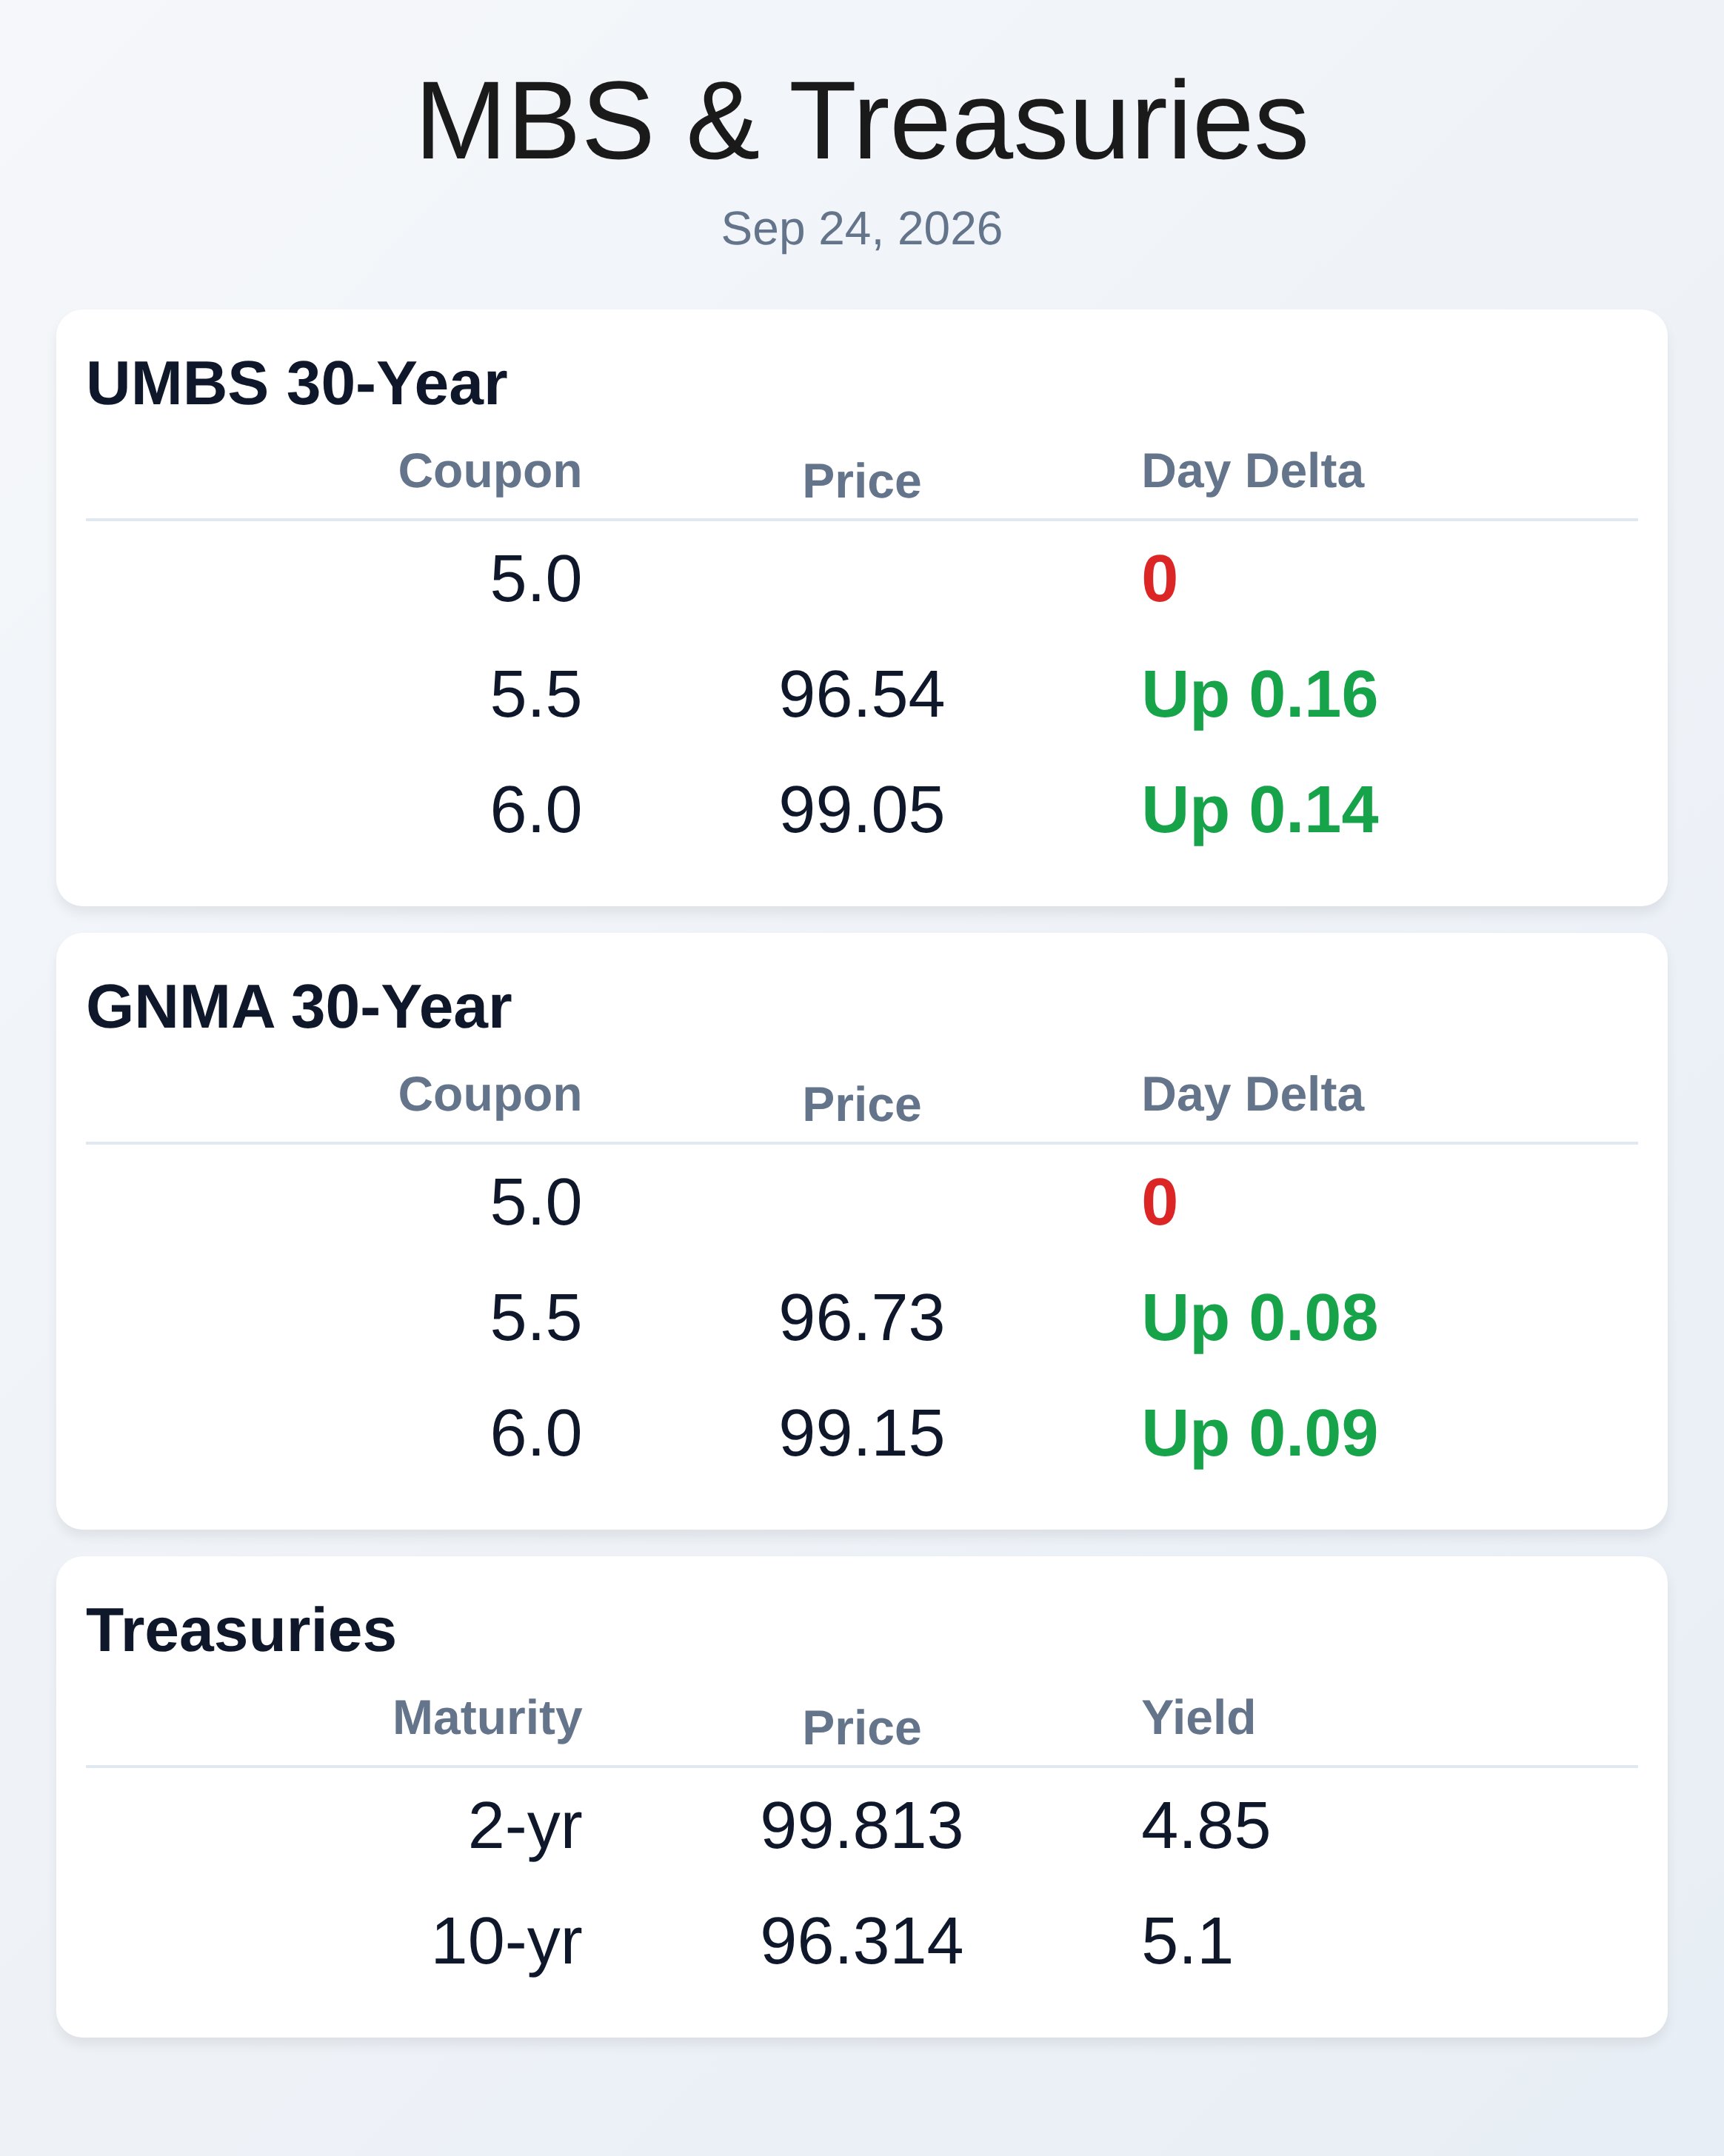
READ MORE **WTMS Blog Today = What's up in Mortgage Today (AM) - 09/24/2026** Bonds suffered their worst selloff in weeks yesterday as yields spiked to 20-year highs across the curve, forcing mortgage rates upward and squeezing originator margins. The 10-year Treasury jumped 14 basis points to around 5.125 percent, while the 30-year approached 5.4 percent, dragging the FNCL conventional coupon up 19 basis points to 6.22 percent. Fast-money traders amplified long-end moves as the market repriced against Fed hawkishness and inflation concerns. The par note rate climbed 15 basis points to a restrictive 7.125 percent, and the probability of an October rate hike surged to 70 percent. This morning, MBS gained 2 ticks while the 10-year backed down 1.9 basis points, but the damage is done and volatility remains elevated. The bond rout was driven by multiple factors converging simultaneously. The preliminary September PMI reading showed a sharp acceleration in U.S. business activity to multi-year highs, stoking recession-prevention concerns and spurring expectations for further Fed tightening. Fed Governor Barr signaled hawkishly that his baseline includes additional policy adjustments, adding credibility to tightening bets. A weak $70 billion 5-year Treasury auction cleared above 5.03 percent with a wide 3.1-basis point tail, revealing that foreign indirect bidders plummeted to just 54 percent. Crude oil futures rose again amid continued Middle East tensions, lifting inflation expectations across the board. Mortgage originators faced a brutal repricing session as spreads widened materially on light volume and rate locks came under pressure. The sharp move in long-end yields hit the mortgage market harder than the short end, which reacted more logically to Fed catch-up tightening. A lender that locked loans yesterday morning faced serious pullback risk, and anyone floating into today's session has to weigh whether prices stabilize or continue deteriorating. The broad-based selloff suggests market participants are genuinely worried about further Fed action and fiscal drag from the mounting budget deficit. For now, the stance remains conservative: wait for a definitive rally before aggressively locking loan flow. The economic calendar is packed today, starting with jobless claims that came in right on forecast at 197,000. Continuing claims eased to 1.719 million versus expectations of 1.750 million, offering a small bit of good news on labor market softness. Later today brings August new home sales, a $44 billion 7-year Treasury auction, and a $6 billion buyback operation in long-dated bonds. Fed speakers are scheduled, and there's also a President Trump and President Xi meeting on the agenda, adding geopolitical uncertainty to an already nervous market. Any additional inflation prints or hawkish commentary could trigger another round of selling. **Locking vs Floating** The technical break above 5.01 percent on the 10-year is a clear warning sign, and there's no telling whether the market will find a bid today or months from now. Until bonds show a definitive shift and rally, the prudent approach is to remain conservative with rate locks and avoid overcommitting to floating inventory. Nerves are running high ahead of next week's economic data, and spreads have widened enough that many originators are pulling back on risk exposure. The default stance since early July has not changed: do not become aggressive until you see a convincing rally. **Today's Events** Jobless Claims (Sep/19): 197.0K vs 201K forecast, 196K previous Continued Claims (Sep/12): 1,719K vs 1,750K forecast, 1,730K previous August New Home Sales (later today) $44 billion 7-year Treasury note auction (later today) $6 billion Treasury buyback operation in 20-year to 30-year bonds (today) Federal Reserve speakers (Fedspeak scheduled throughout the day) President Trump and President Xi bilateral meeting **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | | 2yr | 4.85 | 99.813 | -0.047 | | 3yr | 4.926 | 98.481 | -0.049 | | 5yr | 4.971 | 100.129 | -0.023 | | 7yr | 5.026 | 96.927 | -0.024 | | 10yr | 5.1 | 96.314 | -0.012 | Market Data
Mortgage Today (PM) - 09/23/26 {{catlist}}
September 23, 2026
READ MORE **WTMS Blog Today = What's up in Mortgage Today (PM) - 09/23/2026** UMBS securities tanked today as strong PMI data sparked a bond selloff that pushed the 30-year 6.0 coupon down nearly a full point and sent 10-year Treasury yields rocketing to 5.11%, their highest level since 2007. The shock came at 9:45 a.m. when S&P PMI composite data beat forecasts dramatically, signaling an economy stronger than expected and giving the Fed more room to hike rates. Mortgage lenders scrambled to reprice rate sheets downward as the market deteriorated throughout the afternoon, with many delaying publications to wait for dust to settle. Production margins continue to compress as higher costs and tighter spreads eat into lender profitability. For loan officers, tighter margins mean compensation representing a growing slice of production revenue. The real problem isn't 7% rates—it's that the business model supporting origination has fundamentally shifted while loan officer compensation hasn't adapted. Average loan balances nearly doubled since 2010, swelling from $242,480 in 2015 to $371,965 in 2025, yet lenders still pay originators roughly 92-103 basis points on loan amount. A $500,000 mortgage doesn't require twice the work of a $250,000 loan, but at 100 bps, it pays twice as much. Production profit per loan fell 34% from 2015 to 2025 even though average loan sizes grew 53%, meaning lenders now need 1,515 loans annually just to match what 1,000 loans generated a decade ago—impossible in a 5-million-loan market. Freddie Mac MBS buying could narrow spreads by another 10-12 basis points if the GSE accelerates purchases, according to the Community Home Lenders of America. FHFA Director Bill Pulte said Fannie and Freddie are buying "even more, large quantities" of MBS following three consecutive months of declining holdings. Treasury yields moving in the opposite direction could erase any spread benefits, but for originators competing head-to-head on pricing, even 10 basis points matters. The key metric to watch isn't just the rates originators offer—it's what Fannie and Freddie actually buy each week. UWM introduced Underwriting+, combining processing, underwriting, and borrower communication into a single workflow designed to accelerate closings. Pilot loans averaged just 8.3 days from submission to clear-to-close, reflecting the industry's push for efficiency in tight-margin environments. Loan officers underestimate demand for digital closings, per new ServiceLink research showing a disconnect between what originators think borrowers want and what consumers actually expect. Sagent promoted Sridhar Sharma to CEO as the servicing technology platform continues expanding its Dara offering. Market conditions require conservative lock-and-float decisions even as lenders grapple with whether near-term relief is possible. A clear technical breakout above 5.01% signals nervousness ahead of next week's employment and inflation data, with markets pricing in elevated odds of a second Fed rate hike at the next meeting and two hikes by December. Bonds will likely face more pressure if next week's economic reports confirm the strength shown by today's PMI surge. Lenders should prepare for sustained higher rates rather than betting on a quick reversal. Mutual of Omaha's mortgage division landed on the sale block, surprising even some of its top executives according to sources. Meanwhile, Empower's processing systems reportedly cannot read Excel or Apple Numbers files, creating documentation headaches for loan officers. Better's board is disputing former CEO Vishal Garg's claim that his consent campaign commands 46% of voting power, escalating an increasingly public governance battle. Consumers are fueling additional HEI class action suits amid ongoing scrutiny of the origination platform. **Locking vs Floating** The market has established a clear technical ceiling at 5.14%, a level that should trigger conservative locking strategies if breached. At current levels with 10-year yields near 5.11%, waiting for a definitive rally before floating aggressively makes sense. The default stance remains unchanged since early July: adopt conservative lock positions until market signals a genuine shift lower, particularly ahead of next week's potentially market-moving employment and inflation reports. **Today's Events** S&P Global Composite PMI (Sep): 58.4 vs. 56 previous S&P Global Manufacturing PMI (Sep): 57 vs. 53.6 forecast, 53.9 previous S&P Global Services PMI (Sep): 58.7 vs. 56 forecast, 56.5 previous **Bond Pricing** **UMBS 30 yr** | Coupon | Price | Intra-Day Change | **GNMA 30 yr** | Coupon | Price | Intra-Day Change | **Treasuries** | Term | Yield | Price | Intra-Day Yield Change | Market Data
LATEST ARTICLES

RECENT ARTICLES

Article Archive

Mortgage Marketing Ideas

April 5th, 2019|0 Comments

The Fellas at National Real Estate Post are making a lot of sense about what you are doing wrong with your marketing: https://thenationalrealestatepost.com/red-hat-sea-blue-hats/. Need better tactics? Check out www.WellThatMakesSense.com

April 4th Market Wrap

April 4th, 2019|0 Comments

MBS ended the day pretty much flat. 10 yr treasury also flat in after hours. BLS jobs data tomorrow early. If you can get a lock in before the release tomorrow, might be worth considering.

Most Influential Book on Influence Ever (Tip 6)

April 4th, 2019|0 Comments

This is part of a series of information/stories delivered from the INCREDIBLE book,  "Influence: The Psychology of Persuasion" by Robert Cialdini.     If you work or live a life where you have to get people [...]

April 4th, 2019|0 Comments

"Hey, Read my Email - Read my Email!!!!" isn't very professional.    So I guess we better write better, less-stupid emails when prospecting.    Mark Hunter of "High Profit Prospecting" fame has a [...]

April 3rd, 2019|0 Comments

So stop reading blogs and make calls!

Most Influential Book on Influence Ever (Tip 5)

April 2nd, 2019|0 Comments

This is part of a series of information/stories delivered from the INCREDIBLE book,  "Influence: The Psychology of Persuasion" by Robert Cialdini.     If you work or live a life where you have to get people [...]

April 1st, 2019|0 Comments

A Polite Version of "Get your head out of your as…….." One of my largest literary frustrations is that someone wrote this great, great sales book under an assumed name.   So I can't [...]

March 30th, 2019|0 Comments

** For the Mortgage Peeps It doesn't help lender's relationships with their warehouse banks and correspondent investors when independent mortgage banks, and mortgage subsidiaries of chartered banks, reported a net loss of $200 for [...]

Subscribe

Send me some brain food

Go to Top