“Damn, there is so much great knowledge out there. Did you know that “BOOKS” are full of smart?? No, I mean like life changing, I-wish-I-knew-that-years-ago type stuff.
I know that I was waaaayyy late to the game figuring it out. And I know that a lot of you are too busy to read as much as you ‘should’. And that is why you need me.
I still remember how it started for me. It started in June of 2008. After 11 years …..Click to continue
October 26, 2026
What the Trump Housing Order Actually Means for Your Pipeline
If you've been fielding borrower questions about the October 22 executive order on housing costs, you already know the gap between a White House fact sheet and a funded loan. The order directs federal agencies to pursue several cost-reduction measures, but none of them take effect immediately. What matters now is understanding what the order actually does, what it leaves to agency rulemaking, and how to talk about it with clients without promising savings that may not materialize.An Executive Order Is a Direction, Not a Law
An executive order manages the operations of the Executive branch. After the President signs it, the Office of the Federal Register publishes it. It is not legislation. It does not change underwriting guidelines, fee schedules, or closing requirements on its own. Instead, it directs agencies—in this case, the Federal Housing Finance Agency, the Department of Agriculture, and the Department of Veterans Affairs—to consider or develop specific programs. Those agencies must then write guidance, propose rules, and determine how to implement the directive within existing law and their safety-and-soundness mandates. That process takes time, and the final version of any program may look different from the order's language. For loan originators, the practical instruction is straightforward: do not change how you do business, quote costs, or set borrower expectations until the relevant agency publishes its guidance. The order is a signal of intent, not a switch you can flip today.What the Order Directs: Four Main Actions
According to the White House fact sheet, the order contains four primary directives. First, FHFA must create a pilot program for proactive mortgage insurance cancellation. Under the pilot, Fannie Mae and Freddie Mac would use current property values to cancel borrowers' private mortgage insurance once they meet equity requirements, reducing monthly payments. The pilot would apply only to loans originated after the program begins, which limits relief for existing homeowners. Second, FHFA must make its title insurance waiver pilot permanent, allowing more borrowers to use lower-cost alternatives to traditional title insurance during refinances. Third, the Secretaries of Agriculture and Veterans Affairs must reduce interest rates on single-family home loans made directly by their departments; no target rates were specified. Fourth, the order establishes a Task Force on Manufactured Housing Innovation to improve quality and lower costs for factory-built homes eligible for federal programs. Earlier draft reporting mentioned reviews of loan-level price adjustments, appraisal requirements, and the use of artificial intelligence by the government-sponsored enterprises. The published fact sheet does not mention those items, so treat them as unconfirmed until the full order text appears.The Mortgage Insurance Pilot: Why It's Narrower Than It Sounds
The mortgage insurance provision requires a close read. The pilot calls for proactive cancellation based on current property values, but it covers only loans originated after the program begins. That timing restriction means existing homeowners who might benefit from appreciation-driven equity gains will not see relief under this pilot unless they refinance into a new loan after the program launches. Private mortgage insurance is already designed to be temporary. Under current rules, servicers must cancel MI when a borrower reaches 22 percent equity based on the original amortization schedule, and borrowers can request cancellation at 20 percent equity. FHFA Director Pulte recently aligned the GSEs' policies to allow servicers to proactively contact borrowers who may qualify for cancellation through home price appreciation. The pilot would automate that process using automated valuation models, but only for new originations. U.S. Mortgage Insurers noted that private mortgage insurance premium rates have fallen roughly 25 percent since 2017, driven by competition and tax policy changes. If the government suddenly makes cancellation much easier across the board, insurers will adjust pricing on new loans to offset the revenue lost when more borrowers cancel sooner. That could raise costs for first-time buyers while lowering them for existing homeowners—a trade-off worth understanding before you explain the program to clients.Title Insurance Waiver: Refinance Cost Reduction
The order directs FHFA to make the existing title insurance waiver pilot permanent. That pilot allows certain refinance borrowers to use a lower-cost alternative to a full title insurance policy, reducing closing costs. The Broker Action Coalition estimates potential closing cost savings of approximately $2,390 on an illustrative $500,000 refinance, depending on borrower eligibility and the reforms FHFA ultimately implements. This is the Coalition's estimate, not a savings amount specified or guaranteed by the order. Expanding title acceptance beyond the pilot could streamline refinances and lower costs for qualifying borrowers. The order also directs FHFA to ensure that savings from the expanded program reach consumers and that lenders inform borrowers about the option. Implementation will determine eligibility criteria, which loans qualify, and how servicers and originators incorporate the waiver into their processes. Until FHFA publishes that guidance, the current pilot terms remain in effect.Loan-Level Price Adjustments and Refinance Reforms Under Consideration
The order directs FHFA to consider reducing or eliminating loan-level price adjustments and other enterprise fees on qualifying refinances. It also calls for waiving appraisals and income re-verification where existing data support it. These provisions reach into both pricing and the work required to close a loan, but all of them are for FHFA to consider rather than changes that take effect automatically. MBA estimates that a 0.25-percentage-point fee reduction on a $400,000 purchase loan could save buyers $1,000 at closing. A 0.20-percentage-point reduction in annual FHA mortgage insurance premiums could save borrowers nearly $800 a year. Those figures illustrate the potential impact of fee adjustments, but they are not promises tied to this order. FHFA sets LLPAs for conventional loans, and any change must balance consumer cost, taxpayer risk, and GSE safety and soundness. The order does not address cash-out refinance LLPAs specifically, even though FHFA has the authority to adjust them. Whether the agency will reduce those fees as part of its implementation remains to be seen.USDA and VA Rate Reductions: Direct Lending Only
The order directs the Secretaries of Agriculture and Veterans Affairs to reduce interest rates on single-family home loans made directly by their departments. These are loans the agencies originate and service themselves, not the guaranteed loans that flow through private lenders and make up the majority of USDA and VA volume. No target rates were given, and no timeline was specified. For most originators, this provision will not affect your pipeline. The direct loan programs serve a small share of the market compared to the guarantee programs. If your clients qualify for a USDA or VA guaranteed loan through your shop, this directive does not change their rate or terms. Watch for announcements from the agencies, but do not expect immediate changes to the loan products you deliver to Fannie, Freddie, Ginnie, or portfolio lenders.What to Tell Borrowers Right Now
Borrowers will ask about the order because they will see headlines. Your job is to explain what it means without overpromising. The order directs agencies to build programs, not to cut costs today. No mortgage insurance cancellations, title waivers, fee reductions, or rate cuts are in effect until the relevant agency publishes guidance and updates its systems. If a borrower asks whether they should wait to refinance, the answer depends on their rate, equity, and goals—the same factors that mattered before the order. If waiting six months for a possible title waiver saves them $2,000 but costs them $3,000 in interest, waiting is a bad trade. Run the numbers based on what is real today, not what might happen later. National Association of Mortgage Brokers President Michael Farrell put it clearly: a signed order is a starting point, not the finish line. What matters now is how FHFA, USDA, and VA carry it out. NAMB will be at the table to make sure these changes actually lower costs for borrowers, stay within the law, and protect the broker channel that keeps this market competitive.Your Next Step
Watch for agency guidance from FHFA, USDA, and VA. When those agencies publish their implementation plans, you will know which programs are real, which borrowers qualify, and how to incorporate the changes into your process. Until then, continue quoting costs and setting expectations based on current rules. If a program launches and your borrower qualifies, you can always adjust. If you promise savings that never materialize, you lose trust and waste time. The order signals a policy direction. Your value to clients comes from explaining what that direction means in practical terms and helping them make decisions based on what is real today, not what might be real later. Stay informed on implementation timelines and rule changes so you can advise clients with confidence when these programs go live.
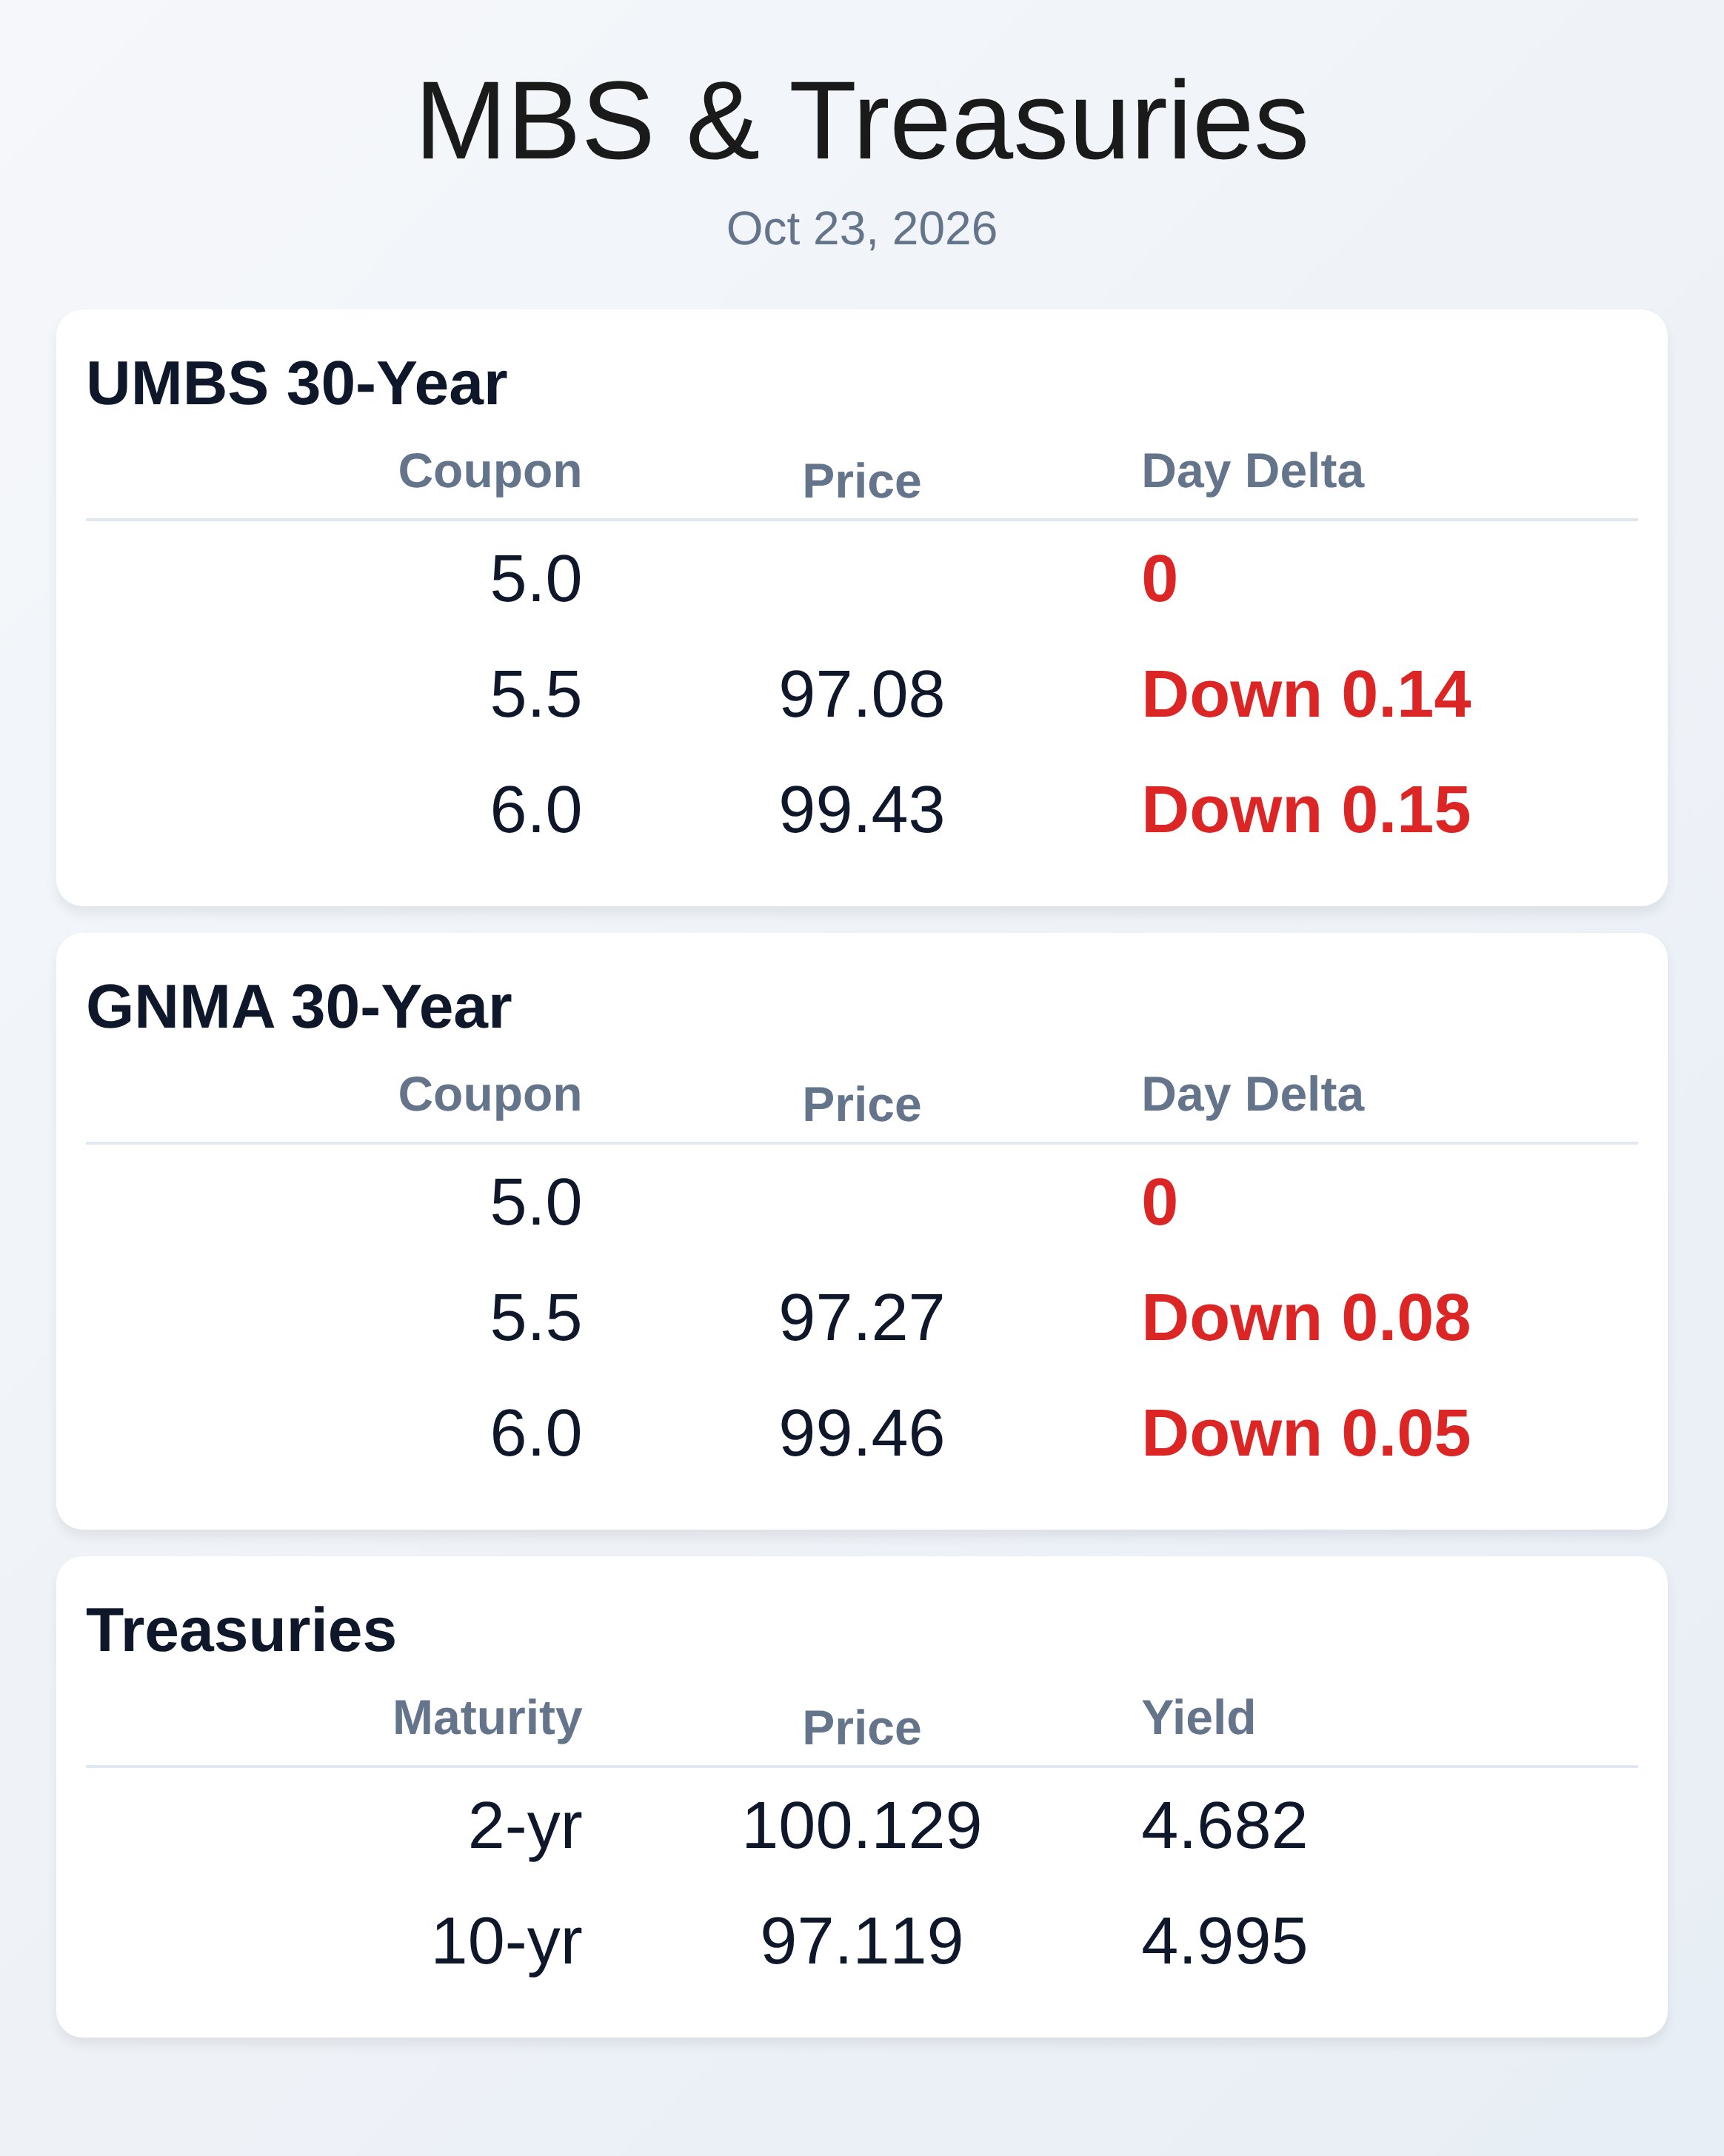
October 23, 2026
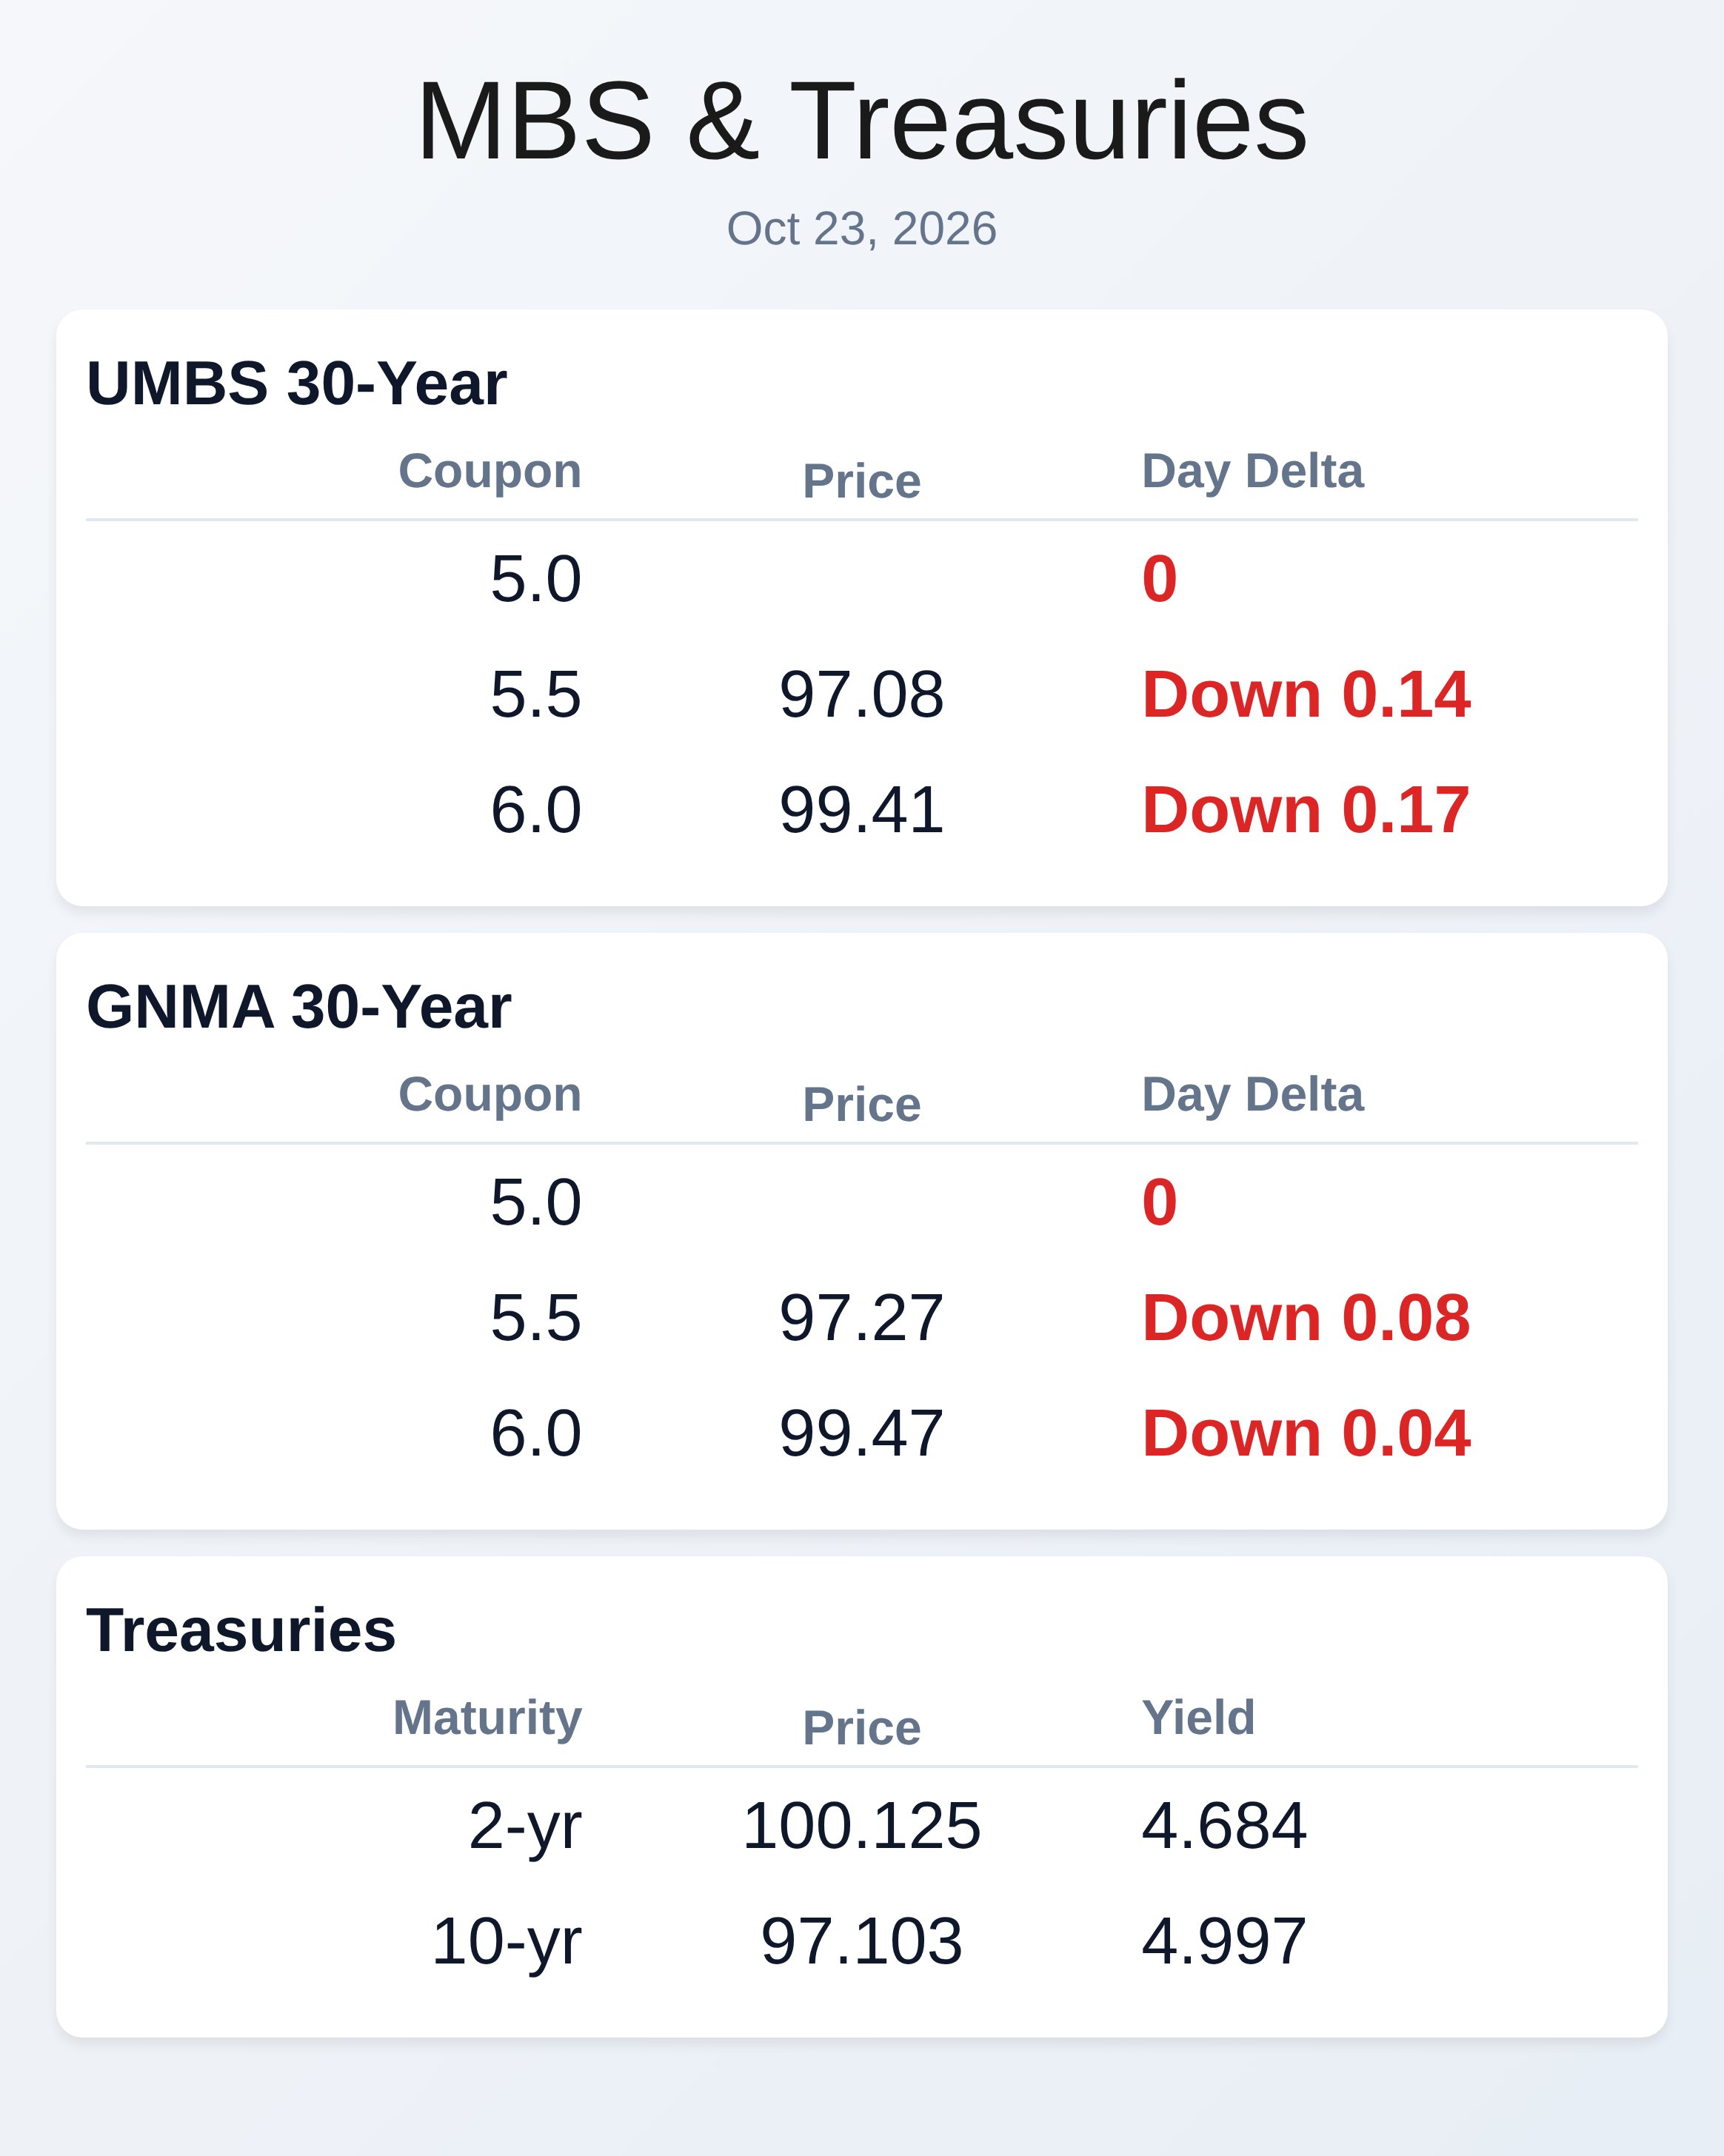
October 23, 2026

RECENT ARTICLES

Why Your $20 ChatGPT Subscription Costs OpenAI $200 to Deliver (And Why That’s a Problem)
Why Your $20 ChatGPT Subscription Costs OpenAI $200 to Deliver (And Why That's a Problem) Inside the eye-watering economics of AI that have tech giants burning through billions faster than a teenager with their [...]
UWM’s Courtroom Drama: When “I’d Rather Not” Meets a Federal Judge
UWM's Courtroom Drama: When "I'd Rather Not" Meets a Federal Judge Mat Ishbia's mortgage empire is playing chicken with contempt charges, and the stakes just got spicier than your compliance officer's nightmare Picture this: [...]
Mortgage Today (AM) – 06/11/26
**WTMS Blog Today = What's up in Mortgage Today (AM) - 06/11/2026** War headlines and producer inflation sent mortgage markets into a tailspin this morning before bonds recovered most losses by mid-morning. May's producer prices [...]
Article Archive
What’s up in Mortgage Today (AM) – 11/21/2025
WTMS Blog Today = What's up in Mortgage Today (AM) - 11/21/2025 Bond markets opened stronger this morning, tracking overnight stock losses as traders positioned ahead of key Fed communications. NY Fed President Williams sent [...]
What’s up in Mortgage Today (AM) – 11/20/2025
WTMS Blog Today = What's up in Mortgage Today (AM) - 11/20/2025 The September jobs report delivered a split decision that kept bond traders on their toes this morning. Nonfarm payrolls came in at 119k [...]
Frame Control for LOs: Own the Room, Own the Result
Frame Control for LOs: Own the Room, Own the Result Every business conversation is a collision of frames—those invisible sets of rules that decide what matters, who leads, and how we’ll judge what [...]
What’s up in Mortgage Today (PM) – 11/19/2025
WTMS Blog Today = What's up in Mortgage Today (PM) - 11/19/2025 Bonds started stronger overnight but surrendered their gains once stocks began recovering at the NYSE open. The 10-year Treasury yield climbed to 4.13% [...]
What’s up in Mortgage Today (AM) – 11/19/2025
WTMS Blog Today = What's up in Mortgage Today (AM) - 11/19/2025 Mortgage rates climbed to a one-month high this week, sending application demand tumbling 5.2%. The 30-year fixed rate hit 6.37%, up from 6.34% [...]
What’s up in Mortgage Today (PM) – 11/18/2025
WTMS Blog Today = What's up in Mortgage Today (PM) - 11/18/2025 Bonds found their footing today despite a confusing return of economic reports after the government shutdown. The 30-year UMBS 5.0 coupon gained 19 [...]
What’s up in Mortgage Today (AM) – 11/18/2025
WTMS Blog Today = What's up in Mortgage Today (AM) - 11/18/2025 Bonds are buying the dip this Tuesday morning regardless of mixed economic data releases. The 30-year UMBS 5.0 coupon jumped 19 basis points [...]
Why Most Mortgage Pitches Fail (and How to Get Past the Croc Brain)
Why Most Mortgage Pitches Fail (and How to Get Past the Croc Brain) If your borrower’s eyes glaze over the moment you start talking basis points, you didn’t lose the deal—you lost the brainstem. [...]